Tepid market response or not, Jabil’s NYSE: JBL recent double-beat earnings report was a buy signal, reinforcing the thesis that has driven shares thus far and strengthening the forward outlook.
Jabil Today
$295.73 +8.87 (+3.09%) As of 10:55 AM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $189.60
▼
$428.93 - Dividend Yield
- 0.11%
- P/E Ratio
- 36.84
- Price Target
- $436.44
AI is driving a surge in demand across the company's product lines, pointing to a sustained upcycle and cash-generating capacity.
Cash-generating capacity is the core thesis, as Jabil is the muscle behind more prominent names such as Apple NASDAQ: AAPL, Cisco Systems NASDAQ: CSCO, and Johnson & Johnson NYSE: JNJ, converting demand for their products into reality.
Jabil’s dividend is a token, yielding less than 0.25%, intended mainly to keep dividend-only funds and institutions in the mix. The firm aggressively repurchases shares and can continue doing so next year.
Highlights from its last fiscal year include about $1 billion in repurchases, up year over year and sufficient to reduce the share count by 3.6%, and a free cash flow payout ratio of about 69%.
Looking ahead, management forecasts free cash flow growth in the coming year, signaling capacity for accelerated buybacks and greater shareholder leverage, which may provide an incentive to buy shares at current levels.
Jabil Boosted by AI, Shows Strengths in All Categories
Jabil posted a solid quarter, with revenue accelerating sequentially and year over year (YOY) to nearly 29%, the fastest pace in more than five years. Revenue growth also outpaced the consensus by a wide margin, approximately 900 basis points (bps), driven by 56% growth in Intelligent Infrastructure. Intelligent Infrastructure did the heavy lifting, but was not the only segment to show strength, with Regulated Industries up by 9% and Connected Living/Digital Commerce flat. CEO Mike Dastoor also highlighted several end markets not related to the data center and AI infrastructure, including automotive, healthcare, energy, defense, aerospace, and warehouse automation.
Margin news was another bright spot. The company faced cost pressures and gross margin headwinds, but they were less than expected and offset by operational quality. Selling, general, and administrative expenses increased at a much slower pace than revenue growth, showing that Jabil is becoming more efficient as it grows, which helped earnings rise faster than revenue. Adjusted earnings per share rose nearly 34% YOY to $4.40, outpacing top-line growth by about 500 bps, with strengths expected to carry into the coming year.
Guidance is a key reason the stock price uptrend is likely to continue. Jabil’s guidance for the next quarter and year is hot on all counts, with revenue and earnings expected to be well above MarketBeat’s reported consensus. The likely outcome is that JBL continues to build momentum, running at the high end of its expected range if not exceeding it, and lifting the year-end outlook along the way.
Analysts Caution Triggers Buying Opportunity in Jabil Shares
Analysts were generally bullish following Jabil’s release, highlighting the revenue strength and earnings quality, but took a cautious stance, focusing on back-end margin expansion and the upfront cost of its capacity buildout. No analysts revised a price target or altered sentiment immediately following the report, leaving the trend unchanged.
The trend includes steady coverage, a Buy consensus with 90% Buy-side bias, and a forecast for nearly 50% upside relative to Q3’s support levels and a fresh all-time high. More importantly, JBL trades well below the lowest analyst price target, signaling a deep-value opportunity and potential for explosive upside as stronger catalysts emerge.
Institutions are likewise bullish on Jabil's stock, citing its cash flow, capital returns, and underlying demand for its clients' products. They own more than 90% of the shares, have bought aggressively over the trailing 12 months, and ramped activity in Q3, reaching a record peak.
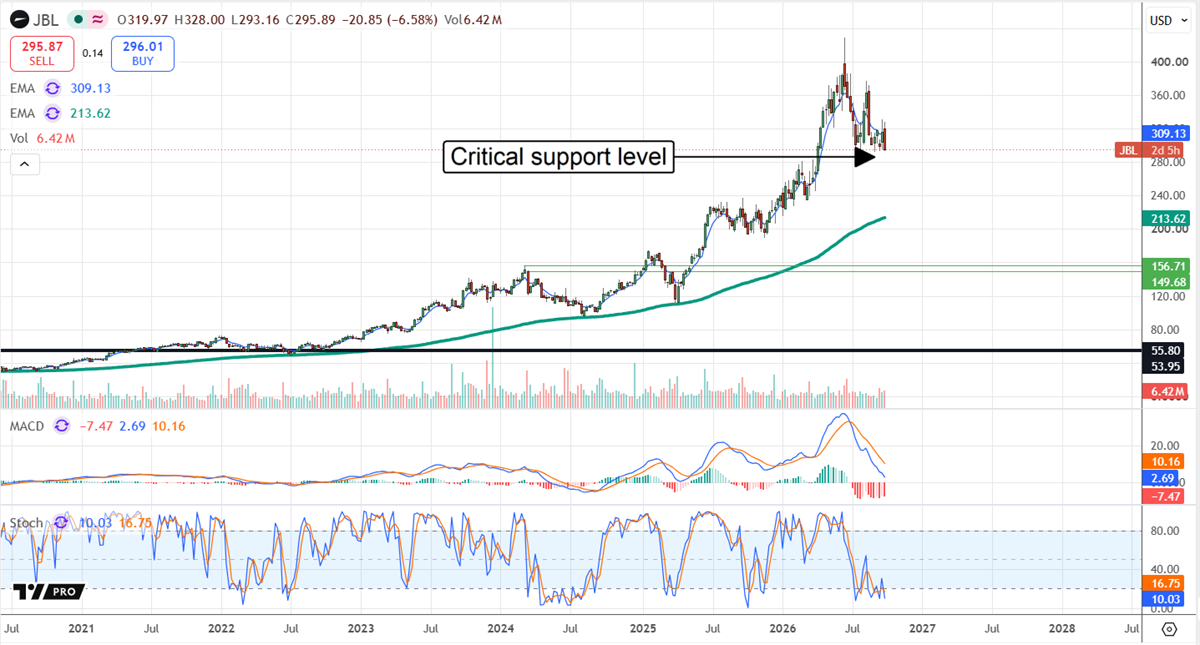
JBL’s price action reflects a bullish market posture. The stock is up more than 35% YOY and more than 100% over the past two years, with the 2026 pullback offering value relative to recent peaks. A deeper pullback is possible, but strong support is evident as September comes to a close, so the risk is minimal. The likely scenario is that JBL remains close to this level until more news becomes available, likely in upcoming earnings reports.
The market may not be getting JBL’s report wrong so much as the price action reflects the split between short-term traders and long-term investors. Short-term traders focus on near-term bottlenecks, AI fears, and capacity costs, and fail to price in the impact on long-term cash flow. Long-term traders, focused on cash flow, capital returns, and capital gains, can easily look past upfront costs and focus on the demand curve, which is improving quarterly across numerous end markets, not just AI.
Jabil’s biggest risk now is executional. Investors need the company's strategy to progress without hiccups, which are likely, given the advanced nature of AI hardware and industry-wide bottlenecks.
Before you consider Jabil, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Jabil wasn't on the list.
While Jabil currently has a Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
The AI boom is creating opportunities across semiconductors, cloud computing, enterprise software, infrastructure, cybersecurity, and automation.
Inside this report, you’ll find 10 companies positioned to benefit as artificial intelligence moves from hype to real-world deployment and becomes a core growth driver for corporate America.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
