Stitch Fix Today
$2.46 +0.31 (+14.19%) As of 01:58 PM Eastern
This is a fair market value price provided by Massive. Learn more. - Price Target
- $3.63
Shares of
Stitch Fix NASDAQ: SFIX fell about 25% in morning trading on Thursday, Sept. 24, after the company announced its
fourth-quarter earnings for its fiscal year 2026 (FY2026). The issue wasn't the results, which were solid, but guidance.
In Q4 FY2026, Stitch Fix delivered revenue of $324.42 million, up 4.2% year over year (YOY). That was slightly below the consensus forecast of $325.5 million, but higher than the $311.23 million it posted in the same quarter a year earlier. It was also the company's sixth straight quarter of YOY revenue growth.
For the full year, Stitch Fix delivered 6.4% YOY revenue growth. That was the first time the company delivered a full year of revenue growth since 2021. The company also generated $19.8 million in free cash flow. It ended the year with $220.9 million in cash and investments and no debt.
The stock is plunging because the company is forecasting that this year's YOY revenue growth may not continue. However, with SFIX trading near its 52-week low, could this be a case of a stock looking so bad that it's actually good?
Guidance Puts the Turnaround Story on Hold
SFIX is under pressure because the full-year guidance for 2027 was for revenue between $1.31 billion and $1.36 billion. The midpoint of that guidance, around $1.335 billion, is lower than the approximately $1.35 billion it delivered in 2026.
In the earnings release, management cited a "more challenging consumer environment" as a key reason for the lower forecast. Like many companies, including McDonald's NYSE: MCD and Dollar General NYSE: DG, Stitch Fix is pointing to a consumer who continues to be choosy with their discretionary spending.
Management also flagged two self-inflicted issues that will weigh on the first quarter. First, the company moved some Fix shipments into Q4, which pulled volume forward from Q1. Second, an unintended change to its post-checkout flow in August limited how many clients could request another Fix. Management says the error has been corrected and won't affect results beyond Q1.
Stitch Fix also plans to spend more on advertising and technology, including artificial intelligence. That's a bet on long-term growth, but it will pressure near-term margins. Investors were hoping the turnaround was gaining speed. Instead, they got a forecast that looks like a pause.
A Good Model With a Poor Moat
The Stitch Fix model is simple and convenient. Customers provide the company with information about themselves, including their lifestyle, measurements, and the types of items they're looking for. The company has a style tool that allows customers to "self-select" the styles and colors that they prefer.
For a $20 fee, the customer gets a curated "Fix" sent to their home. They can choose to keep some, all, or none of the items. If they choose none, the only cost is the $20 fee. If they keep anything, the fee is credited toward their purchase. Furthermore, customers can choose how frequently they receive their orders and even request a Fix on demand to handle upcoming events.
It's a convenient model for the right customer. But maybe too convenient. When customers need to cut items from their budget, subscription services are low-hanging fruit.
To be fair, that's not exactly what the company is reporting. It's not losing customers at the pace it once was. Active clients fell 1.4% YOY to 2.277 million in Q4. That was far better than the 19.6% drop in 2024. But it's not building on that base, either. That puts a lot of pressure on those existing customers to buy more.
So far, they have. Revenue per active client rose 7.8% to $592. Client retention also improved for the eighth straight quarter. The question is how long existing clients can carry the load if their budgets are stretched.
What the Chart Says About SFIX Stock
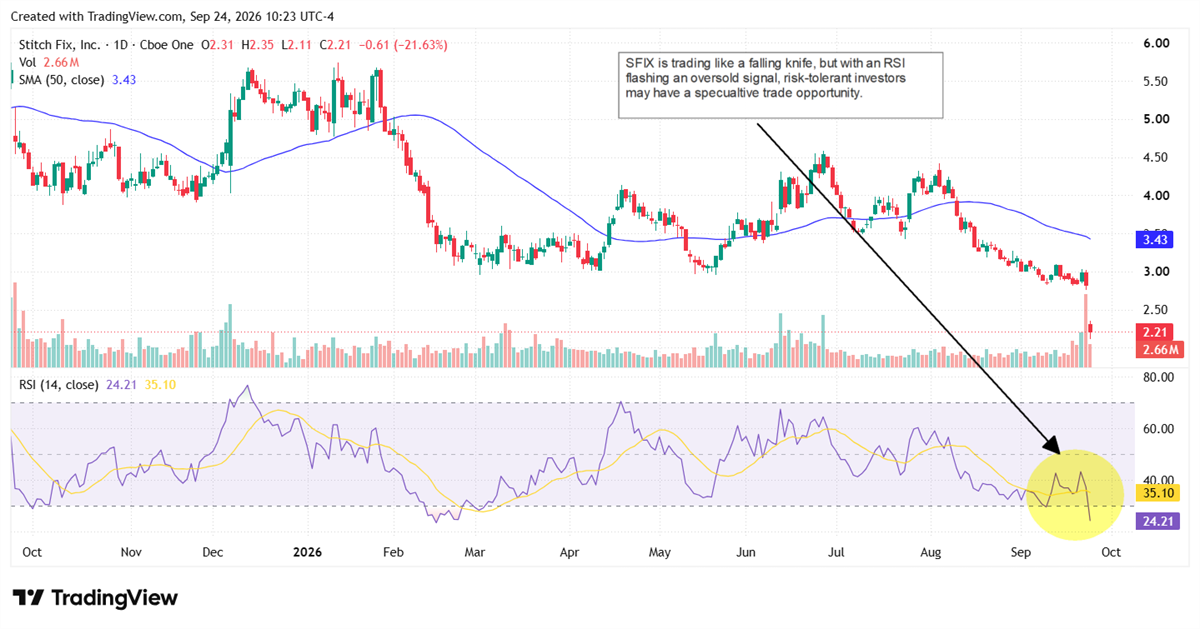
The post-earnings gap lower pushed SFIX decisively below $3. That level acted as support in March and May. The stock had already slipped under it in September, and the earnings report confirmed the breakdown.
The trend is clearly bearish. The 50-day simple moving average (SMA) has been falling since early August and sits at $3.43. SFIX now trades more than 35% below that line. The rallies in April and June both stalled between $4.10 and $4.50, which marks the ceiling bulls would eventually need to clear.
The one bullish signal is momentum. The relative strength index (RSI) dropped to about 24, well below the oversold threshold of 30. The last time RSI sank this low, in February and March, SFIX built a base near $3 for about two months before rallying above $4. Still, oversold is not the same as a bottom. Volume was already elevated by mid-morning, which suggests the selling may not be finished.
Stitch Fix Is a Cautionary Tale, But It's Not a Fairy Tale
Stitch Fix Stock Forecast Today
12-Month Stock Price Forecast:$3.6348.26% UpsideHoldBased on 7 Analyst Ratings | Current Price | $2.45 |
|---|
| High Forecast | $4.00 |
|---|
| Average Forecast | $3.63 |
|---|
| Low Forecast | $3.00 |
|---|
Stitch Fix Stock Forecast DetailsInvestors are wrestling with a stock that's down over 93% in the last five years. But the more significant question is whether SFIX should ever have gone over $95 per share, as it did in 2021.
Investors who took a position in the stock anywhere around that time and thought the sky was the limit are likely hurting badly. Like many stocks at that time, Stitch Fix was a pandemic momentum stock play. It's not that there wasn't any logic to the stock moving higher. In-person shopping was not an option for many customers. The model met the moment.
But the company wasn't profitable then, and it's still not profitable now. The gap, however, is much smaller. Stitch Fix lost $2.1 million in Q4 on a GAAP basis and posted adjusted EBITDA of $10.8 million. In 2022, it lost $207 million.
Putting a $95 price tag on the stock was a fairy tale. With the stock trading near multi-year lows, SFIX is a cautionary tale that rests on the mindset of the consumer. The turnaround has made measurable progress, but the fiscal 2027 outlook puts the burden back on Stitch Fix to prove it can stabilize its client base and resume sustainable revenue growth.
Before you consider Stitch Fix, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Stitch Fix wasn't on the list.
While Stitch Fix currently has a Hold rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Discover the 10 Best High-Yield Dividend Stocks for 2026 and secure reliable income in uncertain markets. Download the report now to identify top dividend payers and avoid common yield traps.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
