Tractor Supply Today
$33.73 -1.00 (-2.87%) As of 10:53 AM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $28.36
▼
$58.20 - Dividend Yield
- 2.85%
- P/E Ratio
- 17.60
- Price Target
- $38.92
These factors include the negative impacts of new store startups, expanded distribution networks, and store closures, all of which affect results today but set the company up for strength in the coming year and beyond. This is important because one of the company’s strengths is cash flow and capital returns, including dividends and share buybacks.
Store closures sound like bad news, but don’t misread the implications. The company identified 75 underperforming Petsense by Tractor Supply stores, deemed them cash-flow negative, and shut them. The company will redeploy the capital to core Petsense operations and growth pillars, including expanding pet services at cash-flow-positive locations. The real story is network growth. While Petsense’s store count contracted, a few new locations cushioned the impact, and growth in Tractor Supply Co.'s locations offset the decline. Its store count grew significantly, driving a 2% year-over-year increase systemwide.
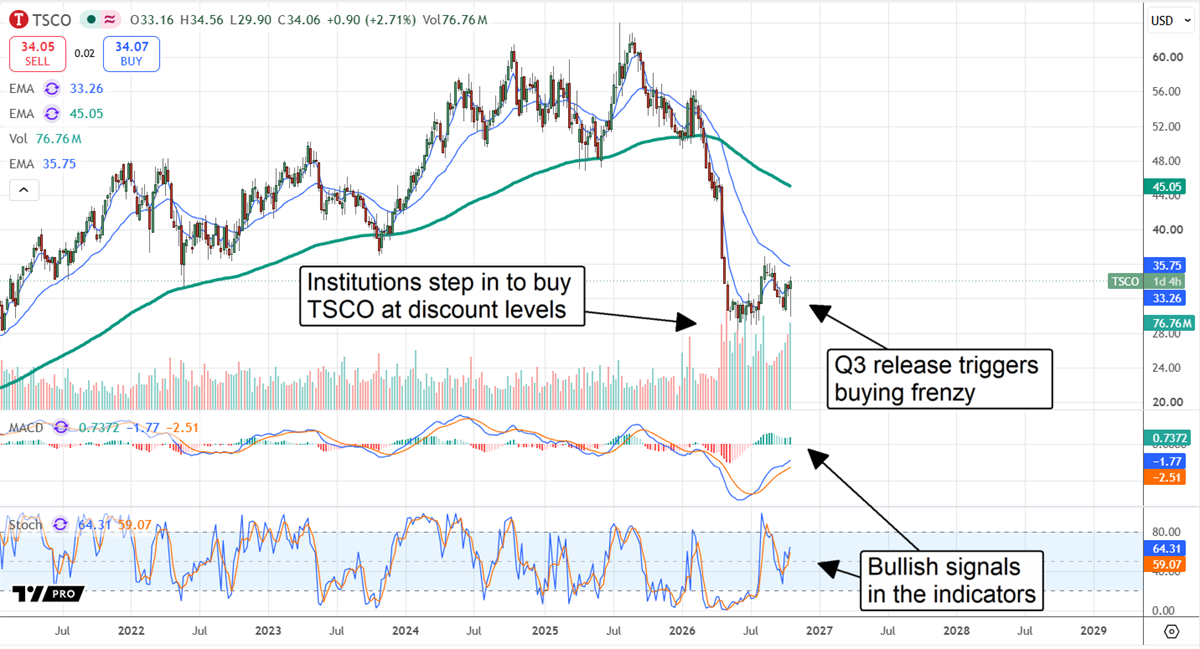
Tractor Supply Outperforms; Sequential Improvements Point to New Momentum
Tractor Supply Company had a decent Q3, with revenue up 5.1% to $3.91 billion. This beat analysts' estimates, supported by comps, new store counts, and acquisitions. Comps, the all-important number, grew by 0.4%, with management highlighting sequential monthly strength as the quarter progressed. This suggests positive trends were in place ahead of the critical holiday season, with strength in seasonal categories.
Margin news is mixed. The company experienced cost pressures across the stack, with the biggest impacts from higher transportation and fuel costs, pricing investments, and startup costs at its new distribution center. Critical details include a 100-basis-point decline in gross margin and a 50-basis-point increase in SG&A expense as a percent of revenue. They led to a 10.2% decline in operating margin, a 13.3% decline in net margin, and a 11.6% decline in diluted earnings per share (EPS), but there is good news. To start, EPS beat estimates by approximately two cents, and the company continued returning capital to shareholders despite weaker margins. To finish, the company may be approaching an inflection point, with management working to accelerate growth and restore margins over the coming years.
Guidance is supportive for share prices and a potential catalyst in that it may be cautious—execs chose to only maintain guidance despite the Q3 strengths. Either way, management expects comps to run flat to slightly down on a year-over-year (YOY) basis, revenue to grow about 3% at the midpoint, and adjusted EPS of about $1.95 at the midpoint, just above consensus.
Capital Returns Drive Market Interest: TSCO Is Well-Supported
Tractor Supply Company’s capital return is attractive and reliable, with a dividend yield of about 2.8% and shares trading near long-term lows. The payout is about 50% of the earnings forecast and is likely to increase annually; TSCO is a Dividend Achiever on track to become a Dividend Champion, with 16 consecutive years of distribution increases that it compounds with share buybacks. Buybacks are opportunistic, taking advantage of cash flow and share prices, with $88.5 million repurchased in Q3. The diluted weighted-average share count fell about 2% year over year, and repurchases could continue while shares trade near their lows.
Tractor Supply MarketRank™ Stock Analysis
4.70282515991 of 5 stars- Overall MarketRank™
- 94th Percentile
- Analyst Rating
- Hold
- Upside/Downside
- 13.0% Upside
- Short Interest Level
- Bearish
- Dividend Strength
- Strong
- News Sentiment
- 0.48
- Insider Trading
- Acquiring Shares
- Proj. Earnings Growth
- 7.73%
See Full AnalysisTractor Supply Company’s balance sheet is not a fortress, but it is solid, healthy, and capable of sustaining strategic moves while returning capital to investors. Quarter-end details include positive cash flow and increased cash and assets, sufficient to offset increases in debt and liabilities. Long-term debt remains under 1x equity, excluding lease liabilities, and equity is growing.
Analysts are responding with cautious relief. Relief focuses on growth and margin, while concerns about margin compression linger, but the view is that long-term recovery is possible. They helped trigger a stock price rebound from an early post-earnings decline, with buyers taking advantage of an early decline to confirm support at the critical level and strong buy signals in the MACD and stochastic indicators. Institutions are the likely buyers; MarketBeat data reveals nearly 99% institutional ownership and accumulation over the trailing 12 months.
Risks include macroeconomic headwinds and shifts in consumer habits. The Q3 results showed strength, but headwinds remain in the form of high gas prices, high inflation, and high interest rates. The risk is that cost-of-living increases constrain consumers, keeping Tractor Supply’s recovery muted and tied to non-discretionary and often lower-margin items. Catalysts include upcoming results and the positive impacts of strategic execution.
Before you consider Tractor Supply, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Tractor Supply wasn't on the list.
While Tractor Supply currently has a Hold rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
AI spending is reshaping the market, and the opportunity extends far beyond the biggest chipmakers. Discover 10 stocks set to benefit from powerful trends in AI infrastructure, cloud computing, energy, capital returns, and consumer growth this fall.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.

