Wall Street may be underestimating monday.com NASDAQ: MNDY.
Despite stronger-than-expected Q3 earnings, weaker Q4 guidance and slowing revenue growth have weighed on the stock. But improving profitability, substantial share repurchases, and new AI initiatives could provide the foundation for a longer-term recovery.
The enterprise software provider is navigating a transition toward AI-driven services while maintaining an established customer base and generating positive cash flow. That combination gives monday.com opportunities to support future growth and potentially return more capital to shareholders, even as near-term challenges persist.
The question is whether these catalysts can offset slowing growth and eventually drive a sustained recovery in MNDY shares.
Aggressive Buybacks Could Set the Stage for More
monday.com doesn’t pay dividends or buy back shares regularly, choosing to use cash flow strategically by buying in lump sums as opportunities and capacity arise.
No shares were bought in Q3, but the company used up an $870 million authorization in the first half of the year, reducing the share count by about 17.85% year over year (YOY).
The company's aggressive buybacks could also set the stage for another round of capital returns, as evidenced by the balance sheet and cash flow. Its Q3 results reflect the impact of earlier repurchases, with cash and equity down sharply, but the company remains well-capitalized and continues to generate positive free cash flow.
A stronger cash position or a new share repurchase authorization could provide another catalyst for MNDY stock.
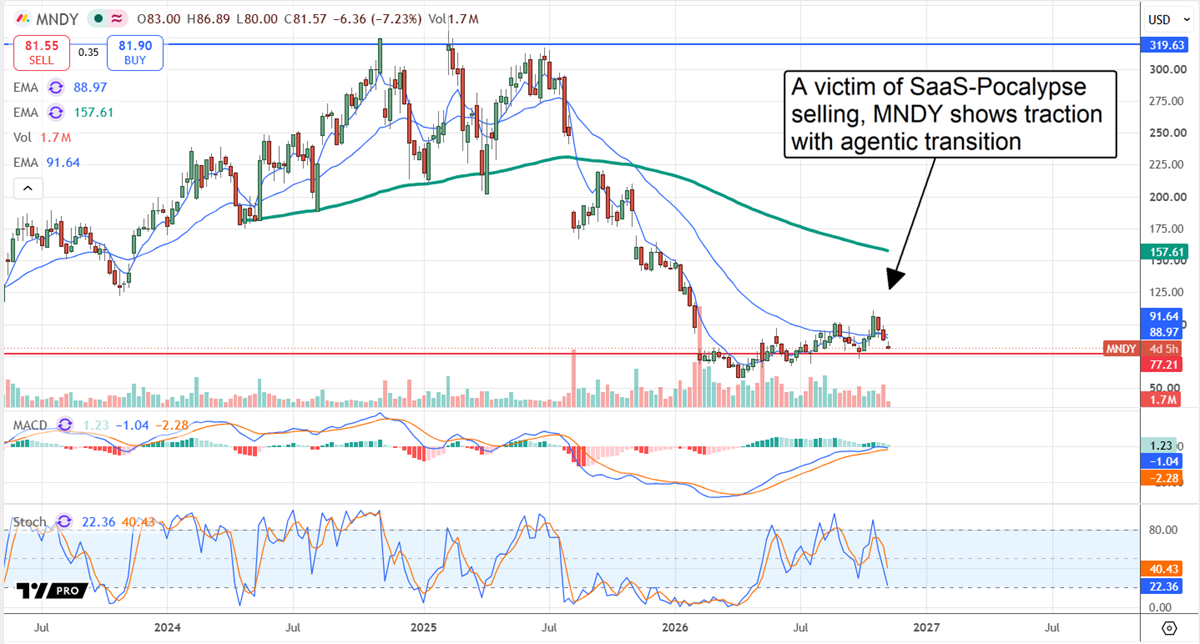
Weak Q4 Guidance Overshadows Strong Earnings and Improving Margins
monday.com Today
$79.93 -8.00 (-9.10%) As of 04:00 PM Eastern
- 52-Week Range
- $57.50
▼
$169.76 - P/E Ratio
- 34.01
- Price Target
- $106.04
One factor weighing on MNDY shares is the company's weaker-than-expectedQ4 guidance, suggesting a sharper-than-expected slowdown in the coming year.
However, investors shouldn't overlook the underlying strength of the company's outlook: management is calling for approximately 14% revenue growth, and full-year forecasts have been revised upward. 2026 revenue is expected to be above the consensus, and the Q3 earnings report offers reasons for optimism despite the slowdown.
Q3 revenue grew more than 19% to $377.5 million, about 2.25 percentage points above the consensus.
Client growth and penetration drove strength, with large clients driving both metrics.
Net dollar retention, which measures revenue growth or contraction among existing customers, was 108% overall, including 112% among customers with more than 10 users and 114% among those generating at least $50,000 in annual recurring revenue (ARR).
Other signs of improving business quality, revenue stability, and customer retention include a growing contribution of larger accounts: the number of customers with more than 10 users increased 5% YOY, and these customers now account for 83% of ARR, up from 81% a year earlier.
Margin news is good, helping to de-risk the near-term outlook and set up the next share repurchase event. GAAP and adjusted operating margin improved nine percentage points, driving GAAP profitability and accelerating earnings growth. Adjusted earnings per share (EPS) grew by nearly 85% to $2.14, outpacing the consensus by a wide margin and suggesting future cash flow strength.
Analysts Take a Wait-and-See Approach to AI Transition
monday.com Stock Forecast Today
12-Month Stock Price Forecast:$107.3532.81% UpsideHoldBased on 25 Analyst Ratings | Current Price | $80.83 |
|---|
| High Forecast | $165.00 |
|---|
| Average Forecast | $107.35 |
|---|
| Low Forecast | $80.00 |
|---|
monday.com Stock Forecast DetailsAnalysts' downward price-target revisions have added to the pressure on MNDY shares, although the consensus price target still suggests upside potential.
Of the 25 analysts covering monday.com, 12 have rated the stock a Buy and 13 have rated it a Hold, resulting in a consensus Hold rating. The average price target stands at $107.35, while the most bearish analyst sees shares falling as low as $80.
Despite acknowledging the company's improving profitability, analysts remain concerned about slowing growth and the execution risks associated with its transition toward larger enterprise customers and AI-driven services. Those concerns are reinforced by management's acknowledgment of operational hurdles, including longer sales cycles and rising costs.
For sentiment to improve, monday.com will likely need to demonstrate that its investments in AI and enterprise expansion can translate into renewed, sustainable revenue growth.
Institutional Ownership and AI Growth Could Shape MNDY's Recovery
Institutional trends also suggest a cautious outlook. Institutions own more than 70% of monday.com's shares, but buying activity fell to historically low levels in 2026, undercutting support.
The question is what could get them back into a more bullish position—and reaccelerating growth and share buybacks could be the primary triggers.
Acceleration isn't guaranteed, but the ongoing transition toward AI-powered enterprise services could create new growth opportunities. One example is Harmony, a voice AI platform launched in October 2026. Designed for enterprise sales teams, Harmony uses AI agents to handle customer calls, qualify leads, and follow up with prospective buyers. The platform could provide monday.com with another avenue for revenue growth as businesses adopt AI tools to automate their sales processes.
What the market may be getting wrong about MNDY in November is placing too much emphasis on near-term headwinds while overlooking the company's established enterprise business and opportunities in AI. Its growing enterprise customer base and new products provide a foundation for future growth, although its ability to drive meaningful revenue acceleration remains unproven.
MNDY shares are trading at a mid-teens multiple of this year's consensus earnings estimates, potentially offering an attractive entry point for investors. Over the next three to five years, the stock could deliver substantial upside if monday.com successfully executes its strategy and achieves its growth forecasts.
Before you consider monday.com, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and monday.com wasn't on the list.
While monday.com currently has a Hold rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Looking for higher dividend income in 2027? Discover seven high-yield dividend stocks with attractive payouts, proven dividend histories and growth potential.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
