Welltower NYSE: WELL just delivered another strong quarter that left investors unimpressed. Shares came under selling pressure following the release of Q3 2026 results that topped estimates on nearly every measure that matters for a REIT.
Welltower Today
$227.97 +1.25 (+0.55%) As of 12:31 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $174.91
▼
$255.20 - P/E Ratio
- 98.70
- Price Target
- $255.76
Heading into the report, the setup was clear. Welltower’s operating story ranked among the strongest in REITs. Yet the stock’s reaction to good news had started telling a different story. The Oct. 27 sell-off makes that disconnect hard to ignore. This is the second straight quarter in which strong results failed to produce lasting gains.
But the numbers shouldn't be dismissed out of hand. Normalized funds from operations (FFO) rose 24.6% to $1.67 per share, beating the $1.64 consensus. Revenue of $3.72 billion also topped forecasts. Management raised full-year normalized FFO guidance to $6.47–$6.53 per share, up from $6.36–$6.44. The board also declared an 85-cent quarterly dividend.
So why the selling? Part of it is a headline problem. Some of it may be a valuation problem. And part of it may be investors looking past this quarter to the next phase of the growth story.
Senior Housing Growth Gives Welltower More Room to Run
Total same-store net operating income (NOI) rose 15.8%, up from 15.5% in the second quarter. The senior housing operating portfolio (SHOP) led again, with same-store NOI up 21%. Occupancy rose 320 basis points year over year. Revenue per occupied room climbed 5.3%, while expenses per occupied room rose just 0.8%. That spread drove 310 basis points of margin expansion.
The supply story held up, too. Welltower says senior housing construction starts are down about 75% from their peak, the lowest level since 2010. Management expects supply to stay constrained through 2030 and beyond. One reason is competition for capital. Data center projects promise returns that senior housing rents can’t match.
Data Science: A Competitive Edge Without a Price Tag
Welltower also highlighted its data science platform, which it began building in 2016. The company says it has screened about 11,500 U.S. communities since 2022 and acquired just 2.8% of them.
It closes deals in 45 to 60 days, versus five to 10 months in a typical marketed sale. In March, Welltower began licensing its models to Public Storage NYSE: PSA and a large private equity firm. Terms weren’t disclosed, and licensing revenue isn’t broken out. The platform supports the case for a premium multiple. Investors just can’t put a number on it yet.
Look Past the Earnings Miss: FFO Tells a Different Story
Some early headlines focused on the earnings miss. They cited GAAP net income of 54 cents per share, versus a 65-cent consensus. But for a REIT, that’s the wrong yardstick. GAAP earnings subtract real estate depreciation, which totaled $707 million last quarter. Net income also swings with one-time gains and charges. FFO exists precisely to strip out that noise.
Still, headlines shape first impressions. A “miss” label on a stock priced for perfection can trigger selling, at least for a session.
Welltower's Premium Valuation Is Becoming Its Biggest Hurdle
Welltower MarketRank™ Stock Analysis
4.434 of 5 stars- Overall MarketRank™
- 89th Percentile
- Analyst Rating
- Moderate Buy
- Upside/Downside
- 13.3% Upside
- Short Interest Level
- Healthy
- Dividend Strength
- N/A
- News Sentiment
- 0.47

- Insider Trading
- Acquiring Shares
- Proj. Earnings Growth
- 16.17%
See Full AnalysisThe bigger issue is valuation. Welltower trades at a premium multiple relative to its 2026 FFO guidance. That’s a premium multiple for any REIT. It assumes the gap between senior housing demand and supply stays wide for years. At that price, a beat-and-raise is the baseline, not the upside.
Growth is also changing shape. Management describes a planned “handover” from occupancy gains to pricing power. Occupancy growth of 320 basis points dipped slightly from 330 in the second quarter. That handover is by design. But pricing-led growth is harder to forecast than filling empty units. Investors paying a premium multiple may want more visibility than that.
Then there’s the cost of growth. Welltower has completed or contracted for $21 billion in investments in 2026. Net debt rose to 3.02 times adjusted EBITDA, up from 2.36 times a year ago. Diluted shares outstanding grew about 10%. Leverage remains low by REIT standards, and S&P and Moody’s both moved their outlooks to positive. But when rates are rising, markets watch closely how growth gets funded.
Interest Rates and Home Equity: The Macro Risks
The macro backdrop hasn’t helped. Welltower’s own presentation notes that the Fed, the European Central Bank, and the Bank of Japan have recently raised rates. Higher rates pressure REIT valuations regardless of operating results.
Record home prices have actually helped Welltower’s customers, many of whom fund their move with home equity. The obvious risk is a housing downturn.
Welltower addressed that directly. Its data shows senior housing occupancy held roughly steady through the financial crisis, even as existing home sales fell nearly 50%. Demand is needs-based. That’s a real argument for resilience. But it’s a fundamentals argument, and right now the stock is trading on perception.
Welltower Stock Faces a Key Technical Test After Earnings
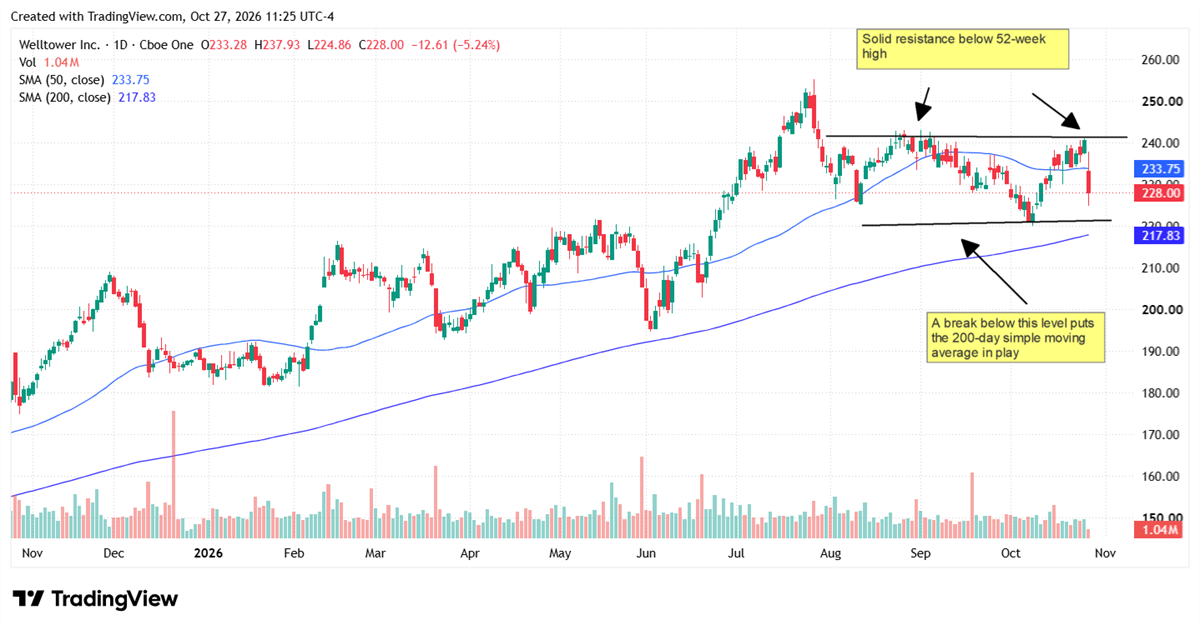
In early trading on Oct. 27, shares fell below the 50-day moving average near $234. At that point, they remained above their 200-day average near $218, which has climbed steadily all year.
The pattern since July is less encouraging. Shares peaked near $255 that month. Rallies in September and October stalled around $240. The early-October low near $221 is the level to watch. A break there would put the 200-day average in play.
Could Welltower's Sell-Off Create a Better Buying Opportunity?
Welltower’s fundamentals delivered again. The market’s response confirmed that strong results alone no longer move this stock. Expectations, not execution, are now the hurdle.
For long-term investors, that disconnect could eventually become an opportunity. For now, the stock likely needs a lower multiple or a fresh catalyst to break the pattern.
Before you consider Welltower, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Welltower wasn't on the list.
While Welltower currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
AI spending is reshaping the market, and the opportunity extends far beyond the biggest chipmakers. Discover 10 stocks set to benefit from powerful trends in AI infrastructure, cloud computing, energy, capital returns, and consumer growth this fall.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.

