Amkor Technology's NASDAQ: AMKR Q3 results left something to be desired, but investors should not mistake weakness in its mobile business for weakness in AI. While AI is central to Amkor’s outlook, its near-term challenges are centered in smartphones. Mobile accounts for as much as 45% of revenue (it varies quarterly), and industrywide headwinds are expected to linger for years.
Amkor Technology Today
AMKR
Amkor Technology
$42.21 +2.27 (+5.68%) As of 04:00 PM Eastern
- 52-Week Range
- $29.76
▼
$96.68 - Dividend Yield
- 0.78%
- P/E Ratio
- 17.02
- Price Target
- $62.50
Wireless carriers have traditionally offered steep discounts on new phones to attract and retain customers, encouraging frequent upgrades.
Verizon NYSE: VZ is among the carriers moving away from that strategy, focusing on service quality and satisfaction instead. Phone upgrades are plunging across the industry, 20% for VZ in Q3, as mobile consumers hang on to phones for longer periods. This trend is reducing demand for new smartphones and, in turn, the semiconductor packaging services Amkor provides.
But it’s not all bad news. Amkor’s mobile business is likely to normalize over time, leaving it a legacy business that may or may not be catalyzed in the future. Meanwhile, the AI industry is booming, helping to offset the decline in mobile.
AI and related industries, including automotive and industrial, are growing at a robust double-digit pace and are expected to remain strong in the coming quarters, likely accelerating as the push for advanced technology and capacity expansion continues.
To capitalize on that demand, Amkor is expanding its operations with support from partnerships with NVIDIA NASDAQ: NVDA, Apple NASDAQ: AAPL, and Advanced Micro Devices NASDAQ: AMD. These investments are helping cement its role as a critical player in AI infrastructure by easing semiconductor production bottlenecks and increasing capacity to meet growing demand.
Amkor's Mixed Q3 Results Reveal a Shift Toward AI
Amkor had a tough quarter, with weakness in the communications segment offsetting strengths elsewhere. Revenue of $1.99 billion was flat year over year (YOY), 245 basis points (bps) below MarketBeat’s reported consensus, offering no catalyst for investors.
Internally, three of the four segments grew sequentially and YOY while communications fell. Computing and Automotive and Industrial segments rose to 48% of net revenue, up 1,100 basis points YOY, which is critical as it reflects the structural pivot toward AI, the higher-margin business.
Margin news was equally mixed, with top-line weakness carrying through to the bottom line. Key details include a 400 bps improvement in gross margin and a 330 bps improvement in operating margin, along with their impact on earnings. Net income grew by 50% on flat revenue, driving 76 cents in GAAP earnings per share (EPS), a 49% YOY gain.
Guidance was a mixed bag, with legacy issues offsetting pivotal strengths. Near-term headwinds include narrowed revenue and earnings forecasts below consensus, but the market may already have priced in the impact. Despite the weak guidance, the stock price responded favorably, suggesting a bottom in AMKR’s pullback.
Amkor’s balance sheet reveals the cost of its expansion plans, with debt doubling, but this is not as much a red flag as at some AI companies. Long-term debt is less than 0.5x equity, with cash up, current and total assets up, equity improving, and leverage low. The likely outcome is that Amkor executes its expansions with relative ease, converts the investments to cash flow, and reduces debt.
Amkor's Pullback Creates Potential Upside
Analysts' trends drove a stock price correction for AMKR in Q3, but the market overreacted, pushing price action below the low end of their range of price targets. While near-term analyst trends remain a headwind, the stock trades at a deep value and could rise more than 50% to the consensus.
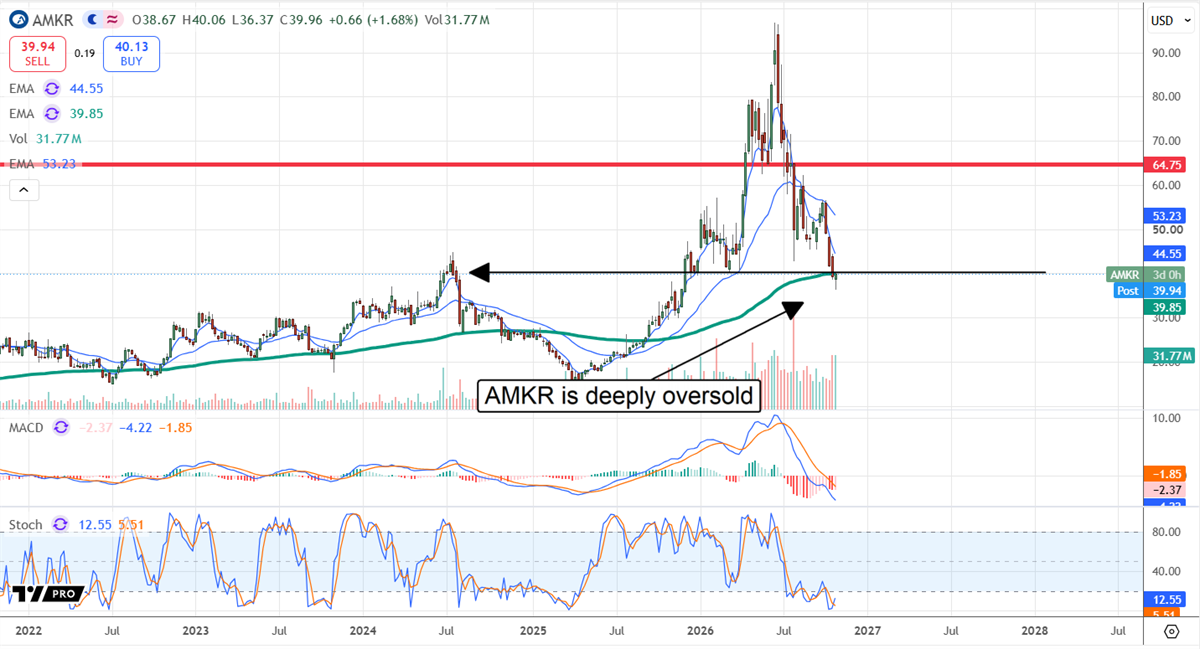
Price action reflects an oversold and overextended market, ready to rebound at the drop of a headline. The stock price is at long-term lows, below a strong support target and the 150-day exponential moving average, and momentum is waning. Indicators such as MACD and stochastic are low in their ranges, with the MACD histogram indicating a divergence from the lows.
Divergence is a critical indicator, highlighting a shifting dynamic which, in this case, reveals the bears losing control and the bulls regaining it. It does not guarantee a market reversal, but it indicates a rebound is likely soon. The likely outcome is that AMKR continues to bottom in Q4, potentially rebounding as high as $50 before hitting resistance. The question is when AMKR will complete a reversal, and that is unlikely to happen until sometime in 2027, when top-line growth resumes.
Amkor’s risks include customer concentration. Its top 10 clients account for the bulk of revenue, about 66% as of Q3, but this is improving. The Q3 data reveals a 600-basis-point improvement in mix, driven by expansion. Expansion includes facilities across the global footprint and advanced packaging needs, effectively turning what the market perceives as risk into a business tailwind.
Before you consider Amkor Technology, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Amkor Technology wasn't on the list.
While Amkor Technology currently has a Hold rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
The AI wave will soon hit public markets with Anthropic and OpenAI set to go public later this year. However, you don't have to wait to invest. This report shows seven AI stocks that you can buy today while the big model providers get ready to go public.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.

