Several factors are driving United Parcel Service’s NYSE: UPS stock price reversal in 2026, all pointing to what matters most to investors: dividend safety.
United Parcel Service Today
UPS
United Parcel Service
$104.52 -1.57 (-1.48%) As of 11:28 AM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $90.84
▼
$122.41 - P/E Ratio
- 19.43
- Price Target
- $116.52
In a world where AI stocks are getting hammered for spending, debt, negative cash flow, and a lack of investor returns, United Parcel Service is among a group of blue-chip, cash-flow-producing companies with attractive dividend yields.
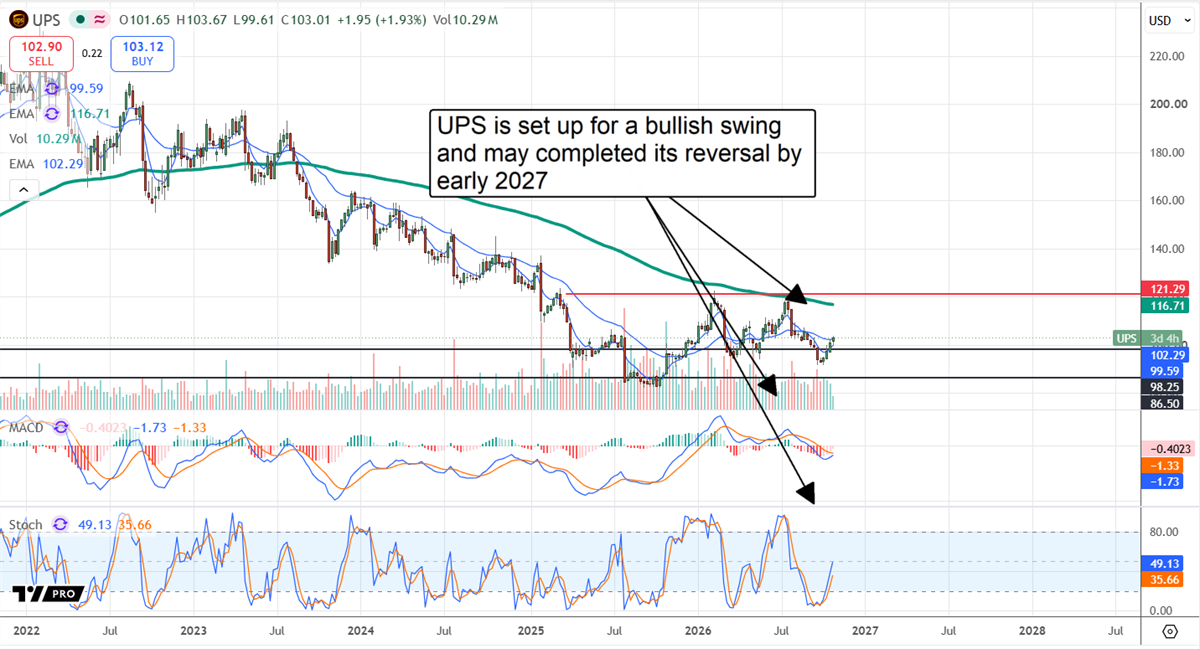
And for UPS, the yield is an extraordinarily high 6.2% because a multi-year downtrend has pushed the stock to historically low levels.
Key takeaways from the company's Q3 release, released on Oct. 27, are expanding free cash flow and dividend coverage.
New guidance forecasts stronger earnings and free cash flow, which would improve payout and coverage ratios and leave a substantial $700 million cushion.
The likely outcome is that UPS will sustain dividend payments in 2027, using its improved free cash flow to accelerate turnaround efforts and balance sheet improvements. Looking ahead, the stage is set for the company to resume share repurchases.
UPS Beats Q3 Expectations as Revenue Growth Accelerates
UPS had a solid quarter, growing revenue by 7% to $22.9 billion, extending its post-Amazon NASDAQ: AMZN recovery. Revenue beat MarketBeat’s reported consensus by 2.6%, supported by strength across all segments. The core domestic segment grew by 4.5%, while International and Supply Chain Solutions (SCS) drove more substantial improvements. International grew 7%, with a 15% increase in revenue per package offsetting volume losses, while SCS grew 18.2%, supported by healthcare initiatives.
UPS is leaning into specialized services, including healthcare, to offset declines in core package volume. The plan includes doubling the business to $20 billion in annualized revenue, and the company is well on track to meet its goals. Services include cryogenic temperature control and systems integration to speed deliveries.
Margin news was mixed but highly favorable to investors. The headline was a 100 basis-point contraction in the adjusted operating margin to 9%, far less than analysts had feared. The net result was $2.1 billion in adjusted operating income and $1.69 in adjusted earnings per share (EPS), 7 cents better than expected, with guidance indicating the company's momentum will continue.
Optimistic Analysts Reinforce UPS Price Floor
UPS's analyst trends have been tepid, with 26 analysts rating the stock a consensus Hold and recent price target revisions trending downward. However, investors shouldn’t misread these trends. Analysts reflect confidence in the long-term outlook and provide a floor for the stock price that recent price action has confirmed.
This floor is in the low-$80s and unlikely to be broken unless UPS's fundamental outlook changes. The more likely scenario is that sentiment remains stable in Q4 while the market waits to see what happens next. Q4 earnings and 2027 guidance are expected in late January and will be a near-term touchpoint on the company's outlook.
The post-release price action was favorable. UPS shares advanced about 5%, confirming near-term support and the potential for a continued rebound. The stock could rise toward the consensus price target in Q4, likely no higher than $120, unless catalysts such as bullish holiday spending figures emerge. Longer term, UPS is on track for a full share price recovery, but revenue growth, cash flow, and capital returns will take time to do their work.
UPS Still Faces Risks Despite Its Improving Outlook
Institutions are a factor investors need to watch. The group owns 60% of the shares and has been accumulating, but the pace of accumulation is slow. The Q3 results may prompt them to adopt a more bullish posture, given the high yield and improved analyst coverage, helping cement the price floor and the upside potential. Triggers for this group to keep buying include an improved capital-return outlook and, more importantly, increased capital returns, including dividend increases and share buybacks.
UPS's biggest risks include competition, labor relations, and geopolitical issues. Competition is tougher quarter by quarter; legacy carriers vie for volume while disruptors like Amazon nibble away at the market. Labor relations threaten both top- and bottom-line growth, with strikes potentially impacting current business and future cash flow, and geopolitical issues make business tougher across the board.
The market got it wrong to punish UPS for its Amazon-related volume loss. The move decoupled the business from volume, turning it into a higher-margin, higher-quality machine capable of sustaining cash flow. Execs trimmed billions in costs, shuttered unneeded facilities and used technology to streamline operations, supporting the sticky operational improvements institutional investors want to see before becoming more confident in future capital returns.
Before you consider United Parcel Service, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and United Parcel Service wasn't on the list.
While United Parcel Service currently has a Hold rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Discover the next wave of investment opportunities with our report, 7 Stocks That Will Be Magnificent in 2026. Explore companies poised to replicate the growth, innovation, and value creation of the tech giants dominating today's markets.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.

