Boot Barn (NYSE:BOOT - Get Free Report) issued an update on its FY 2027 earnings guidance on Friday. The company provided earnings per share guidance of 8.720-9.000 for the period, compared to the consensus earnings per share estimate of 9.020. The company issued revenue guidance of $2.6 billion, compared to the consensus revenue estimate of $2.6 billion. Boot Barn also updated its Q3 2027 guidance to 3.030-3.190 EPS.
Wall Street Analyst Weigh In
A number of brokerages have weighed in on BOOT. Piper Sandler restated an "overweight" rating and issued a $187.00 target price (down from $226.00) on shares of Boot Barn in a research report on Thursday. Weiss Ratings cut Boot Barn from a "hold (c+)" rating to a "hold (c)" rating in a report on Friday, October 23rd. Zacks Research downgraded Boot Barn from a "strong-buy" rating to a "hold" rating in a research note on Tuesday. Citigroup dropped their price objective on shares of Boot Barn from $205.00 to $180.00 and set a "buy" rating for the company in a report on Tuesday, October 13th. Finally, BTIG Research reduced their target price on shares of Boot Barn from $215.00 to $195.00 and set a "buy" rating on the stock in a report on Thursday. Thirteen equities research analysts have rated the stock with a Buy rating and two have issued a Hold rating to the stock. According to MarketBeat.com, the company has an average rating of "Moderate Buy" and a consensus price target of $193.00.
Check Out Our Latest Stock Report on BOOT
Boot Barn Trading Up 15.0%
Shares of NYSE BOOT opened at $130.35 on Friday. Boot Barn has a 1-year low of $110.53 and a 1-year high of $210.25. The firm has a market capitalization of $3.95 billion, a P/E ratio of 15.78, a P/E/G ratio of 0.74 and a beta of 1.76. The firm's 50-day moving average price is $131.72 and its 200-day moving average price is $158.68.
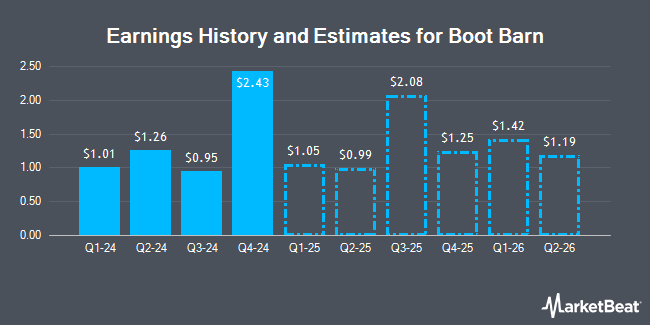
Boot Barn (NYSE:BOOT - Get Free Report) last posted its quarterly earnings results on Wednesday, October 28th. The company reported $1.73 earnings per share (EPS) for the quarter, beating the consensus estimate of $1.63 by $0.10. Boot Barn had a net margin of 10.45% and a return on equity of 19.04%. The business had revenue of $581.81 million during the quarter, compared to the consensus estimate of $580.80 million. During the same quarter last year, the firm posted $1.37 EPS. Boot Barn's revenue was up 15.1% compared to the same quarter last year. Equities research analysts forecast that Boot Barn will post 9.06 EPS for the current year.
Boot Barn News Summary
Here are the key news stories impacting Boot Barn this week:
- Positive Sentiment: Boot Barn reported fiscal Q2 revenue of approximately $581.8 million, up 15.1% year over year, while diluted EPS rose 26.3% to $1.73, beating the $1.63 consensus estimate. Gross profit, operating income and operating cash flow also increased, reflecting margin gains and improved profitability. Boot Barn fiscal Q2 results
- Positive Sentiment: The company authorized an additional $400 million for share repurchases, which could support per-share earnings and signal management confidence in the long-term outlook. Boot Barn also raised its full-year store-opening target to approximately 80 locations and plans to continue expanding its retail footprint. Boot Barn share repurchase authorization
- Neutral Sentiment: Boot Barn’s commercial business, Boot Barn Workforce, generated about $100 million in sales during the previous fiscal year, providing an additional growth channel beyond consumer retail. Boot Barn long-term investor takeaways
- Negative Sentiment: Management’s fiscal Q3 guidance calls for EPS of $3.03–$3.19 and revenue of $785 million–$802 million, below consensus estimates of $3.42 and $816.2 million, respectively. Full-year fiscal 2027 EPS guidance of $8.72–$9.00 also trails the $9.02 consensus, although the $2.6 billion revenue outlook is in line with expectations.
- Negative Sentiment: The combination of a sales shortfall and lower outlook has prompted cautious analyst reactions. Robert W. Baird reduced its price target from $160 to $145 while retaining an “outperform” rating, and Zacks Research downgraded the stock from “strong buy” to “hold.” Baird Boot Barn rating
About Boot Barn
(
Get Free Report)
Boot Barn Holdings, Inc is a specialty retailer focused on Western and work-related apparel, footwear and accessories. The company sells products including cowboy boots, work boots, jeans, shirts, hats, outerwear, belts and other accessories from a range of national and private-label brands.
Boot Barn serves customers through a network of retail stores across the United States, as well as through its e-commerce platform. Its merchandise is marketed to Western lifestyle customers, workers who need durable clothing and footwear, and consumers participating in activities such as rodeo, riding and outdoor recreation.
The company traces its beginnings to 1978 and is headquartered in Irvine, California.
Further Reading
This instant news alert was generated by narrative science technology and financial data from MarketBeat in order to provide readers with the fastest reporting and unbiased coverage. Please send any questions or comments about this story to contact@marketbeat.com.
Before you consider Boot Barn, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Boot Barn wasn't on the list.
While Boot Barn currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
The AI boom extends far beyond the biggest tech names. Discover 10 companies supplying the memory, storage, networking, semiconductor manufacturing, and power infrastructure that make AI possible. Learn where the next wave of AI investment opportunities may emerge—and the key risks investors should watch as the global AI buildout accelerates.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.

