Share buybacks matter for many reasons, including earnings-per-share boosts, dilution offsets, tax efficiency, shareholder leverage, and signals of management confidence. They matter much more for big tech companies because the industry is in the midst of a shift that amplifies these signals.
The shift is from traditional, asset-light models reliant on software revenue toward heavy investment in infrastructure and data centers. Those investments weigh on cash flow today through upfront costs and on future earnings through depreciation, maintenance, and upgrades. The question is which companies can maintain or accelerate capital returns despite that, and which can't, because that matters for share price action.
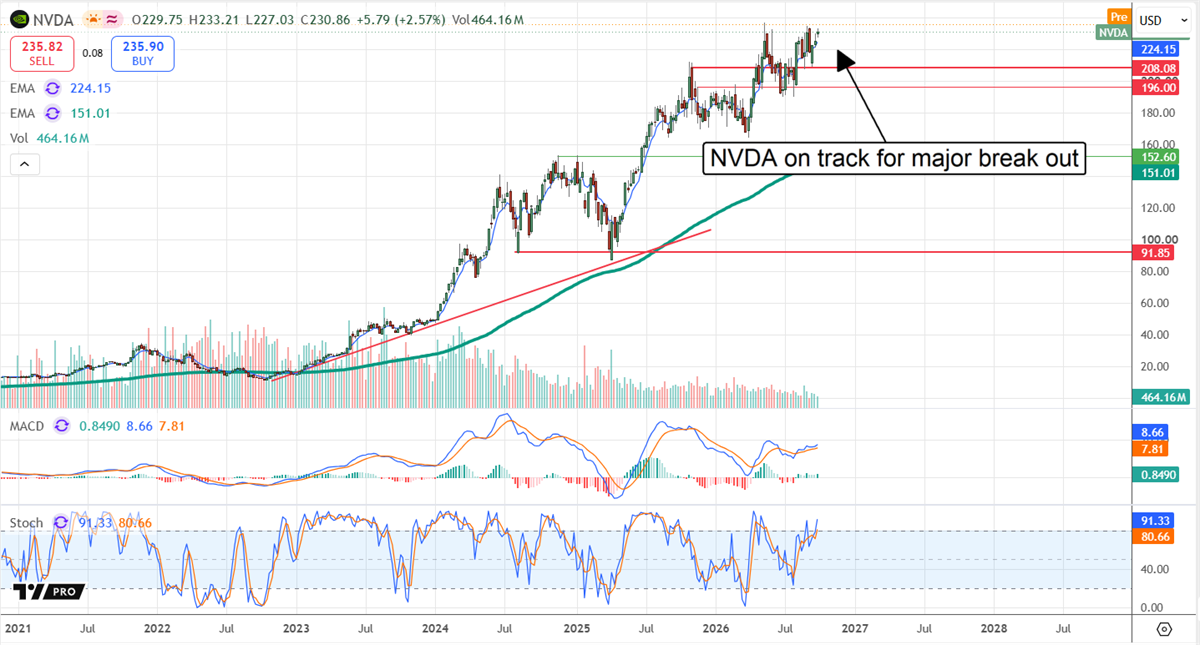
NVIDIA Sends Strong Signal That Cash Flow Is Healthy
NVIDIA NASDAQ: NVDA is the most important stock in the market for its technology, market cap, and capital-flow centricity.
NVIDIA Today
$238.90 +4.95 (+2.12%) As of 04:00 PM Eastern
- 52-Week Range
- $164.27
▼
$240.10 - Dividend Yield
- 0.42%
- P/E Ratio
- 30.20
- Price Target
- $321.89
AI dollars flow toward it as the source of GPUs, interconnect technology, and its all-important CUDA programming architecture. It recently announced a $150 billion increase to its share buyback plan, sufficient to lift it above $225 billion, approximately 4.2% of market cap, and it’s expected to be used over the next 16 months.
NVIDIA’s buyback plans are reliable, backed up by cash flow and a fortress balance sheet. The company’s cash flow has grown over the past few years and is on track to top $150 billion in fiscal 2027, with free cash flow (FCF) conversion in the 95% to 97% range. Balance sheet highlights include about $22 billion in cash (despite acquisitions and reinvestment) at the end of the first half, marketable securities of more than $75 billion, and receivables and inventory of about $95 billion, providing clear insight into future cash flow and capital-return power.
Salesforce Gets Aggressive With Buybacks
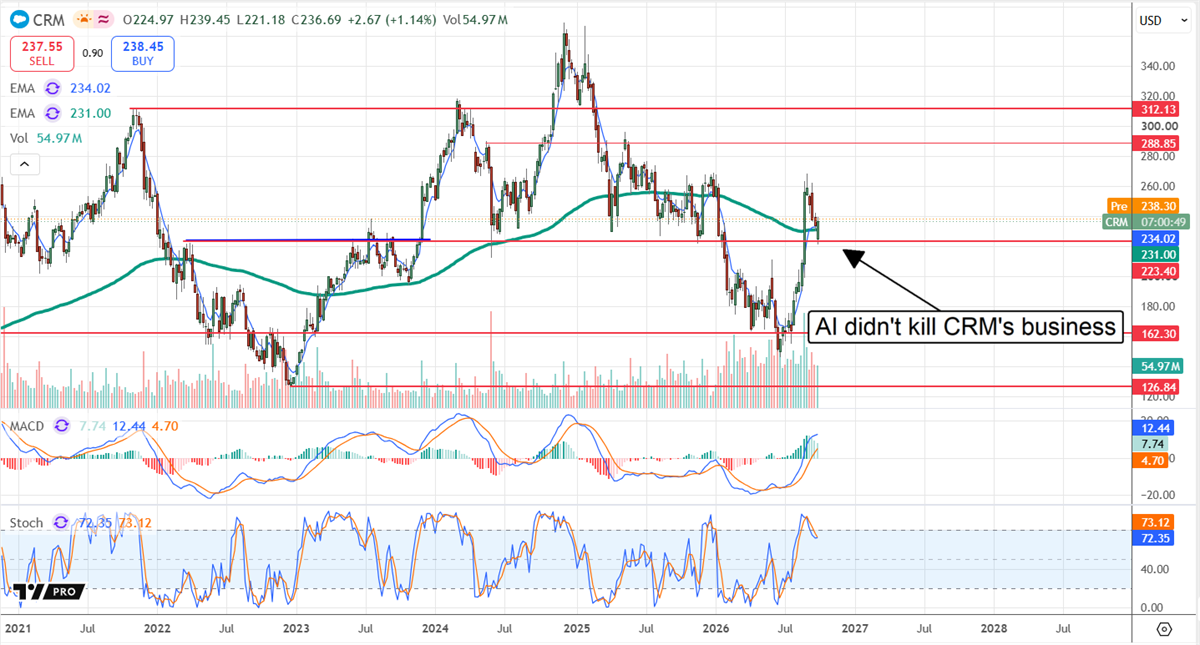
Salesforce NYSE: CRM authorized $50 billion in buybacks in early 2026 and is aggressively executing, with a $25 billion accelerated share repurchase plan in effect.
Salesforce Today
$229.62 -5.07 (-2.16%) As of 03:59 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $146.32
▼
$269.11 - Dividend Yield
- 0.77%
- P/E Ratio
- 20.93
- Price Target
- $275.14
The latest report revealed a 14.6% year-over-year reduction in share count, and the pace will likely continue. The company has another $25 billion left under its authorization, worth nearly 13% of its market cap.
Salesforce’s buyback is reliable because its results reveal increasing momentum in its AI and agentic AI segments. These drivers support outperformance and market confidence, with future results likely to continue the trend. The buyback is also reliable because cash flow and free cash flow are sufficient to sustain the payment while whittling down newly acquired debt, and the debt may not even be an issue.
CEO Marc Benioff is considering an asset sale that could wipe the debt off the books forever. The only catch is that the asset is its Anthropic stake, a major customer Salesforce doesn’t want to lose.
Adobe Builds Solid Foundation for Share Price Rebound
Adobe Today
$238.79 +1.10 (+0.46%) As of 04:00 PM Eastern
- 52-Week Range
- $190.12
▼
$363.70 - P/E Ratio
- 13.33
- Price Target
- $282.68
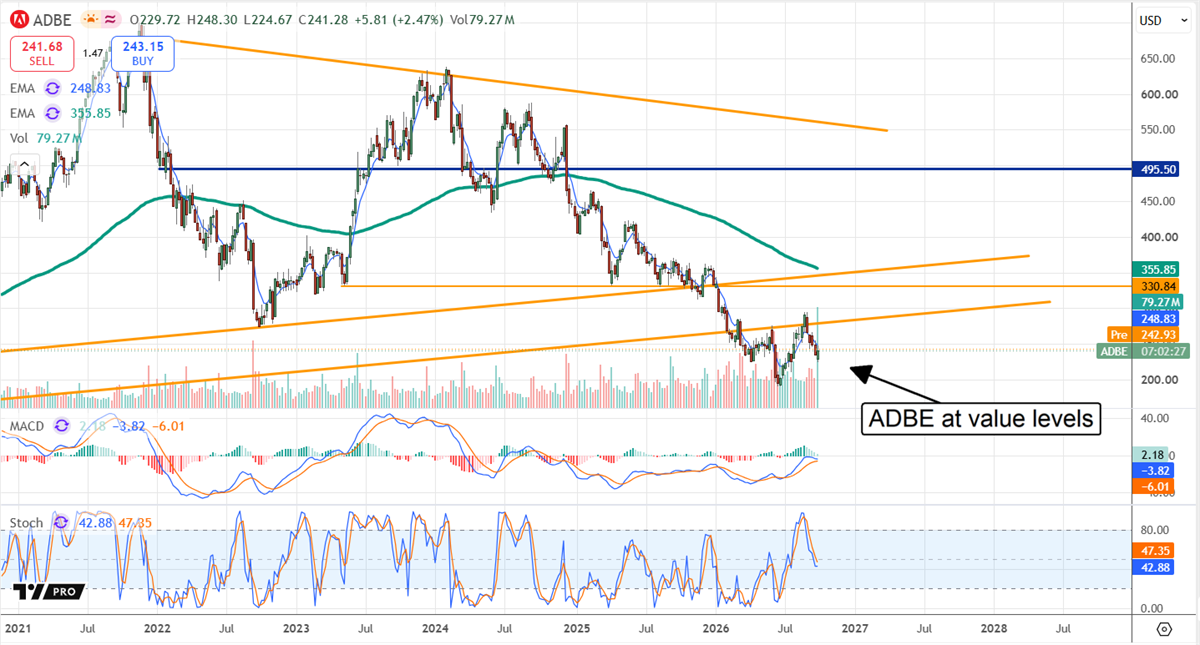
Adobe’s NASDAQ: ADBE share price is weighed down more by market angst than anything else, even though its buyback is healthy, reducing the share count by more than 6% in the first nine months of fiscal 2026.
The existing authorization is winding down, but an additional authorization is likely, given the company’s growth and cash flow, which reached record levels in Q3.
Adobe’s drivers include enterprise workflows, protected by its PDF moat, which make it ubiquitous across cloud environments.
Attractions in 2026 include the dicounted stock price, which is hovering near multi-year lows, enabling the company to lean into share count reduction.
Qualcomm Quietly Reduces Its Share Count, Poised for Explosive Growth
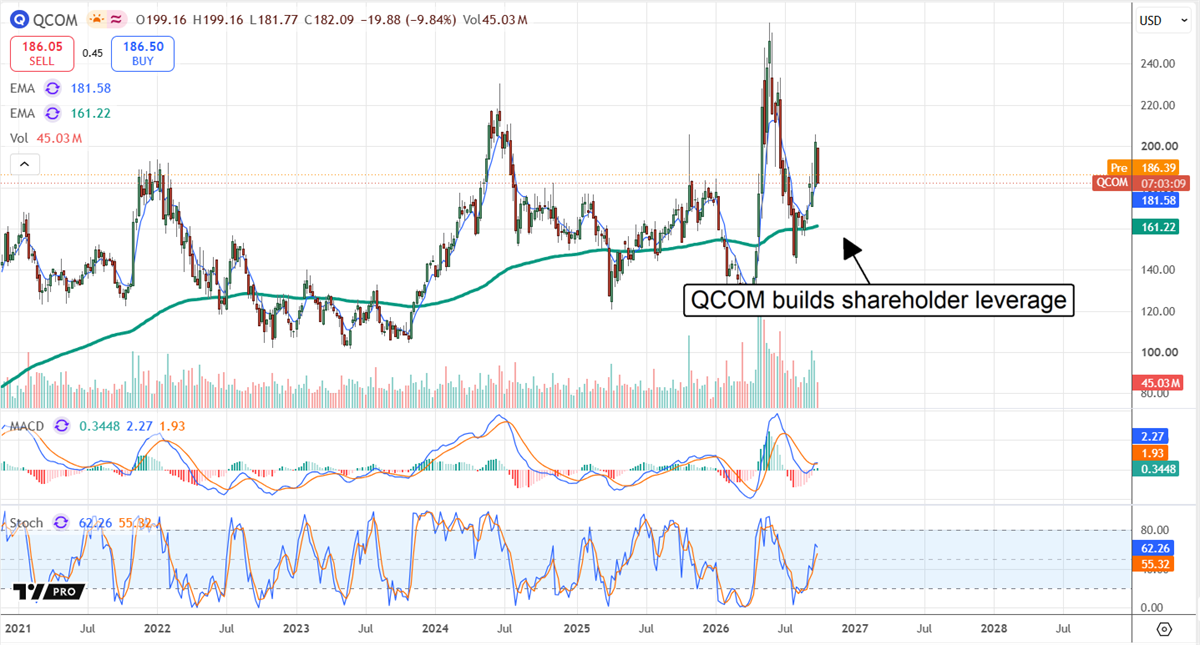
Qualcomm NASDAQ: QCOM is well-positioned as a supplier of advanced semiconductor technology for mobile devices.
Qualcomm Today
$180.79 -4.08 (-2.21%) As of 04:00 PM Eastern
- 52-Week Range
- $121.99
▼
$259.92 - Dividend Yield
- 2.04%
- P/E Ratio
- 20.92
- Price Target
- $204.10
Its moat is solid, built on patents and industry-leading technology, and it earns royalties from virtually every mobile device maker. Its position enables reliable cash flow and a healthy buyback program that reduced its share count by 3.5% in the first nine months of the year.
Qualcomm is positioned for explosive growth because it sits at the edge of computing between consumers and AI. It will surf the AI wave once it reaches the consumer level, a process that has begun but has not yet reached critical mass. Looking ahead, analysts forecast an inflection in late 2027, including a return to revenue and earnings growth.
Until then, the company’s cash flow and balance sheet cover the capital return, leverage is light, and equity is improving quarter over quarter.
Jabil Helps Monetize AI Demand
Jabil Today
$300.77 -3.64 (-1.19%) As of 03:59 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $189.60
▼
$428.93 - Dividend Yield
- 0.11%
- P/E Ratio
- 30.75
- Price Target
- $434.22
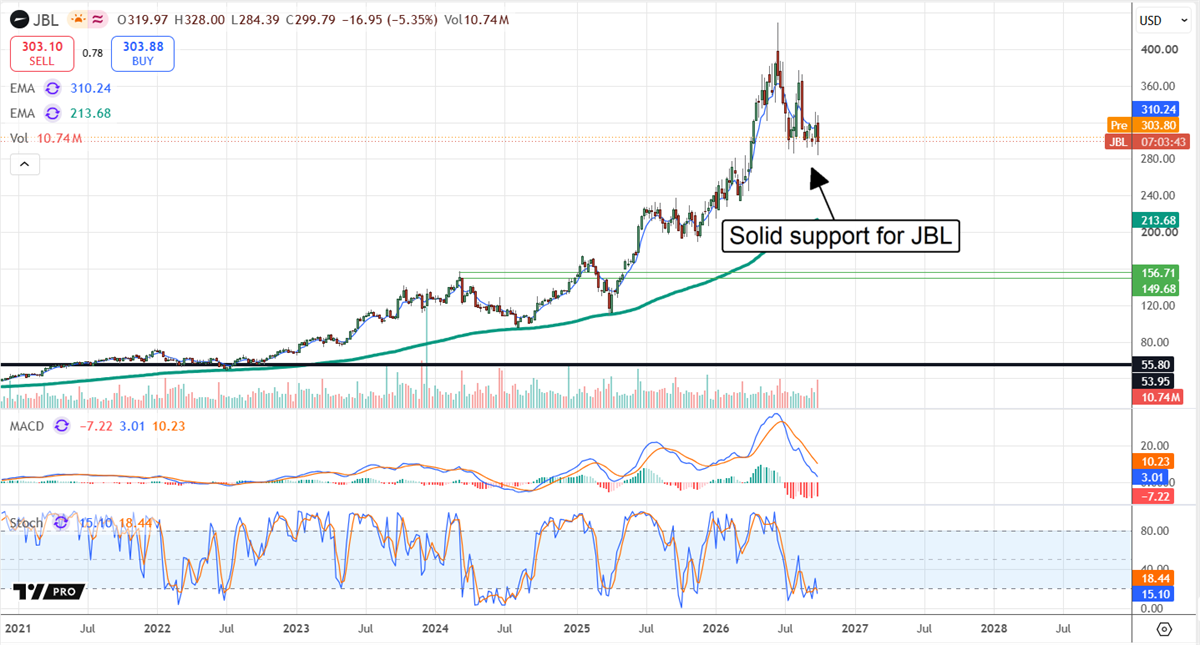
Jabil, Inc. NASDAQ: JBL is a key component of the AI supply chain, manufacturing products for companies such as Amazon NASDAQ: AMZN, Alphabet NASDAQ: GOOGL, Hewlett Packard NYSE: HPE, and Cisco Systems NASDAQ: CSCO. As such, it is uniquely positioned to monetize AI and is committed to share buybacks. The company leans on buybacks as the foundation of its capital return, which includes a dividend.
Jabil’s yield is among the lowest, but buybacks matter, reducing the share count by 3.6% in fiscal 2026.
Its payout is reliable because of strong cash flow and a solid balance sheet, supported by its 2027 guidance. Guidance forecasts a 24% revenue increase, driven by AI/datacenter demand and broad-based strength in other key end markets.
Before you consider NVIDIA, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and NVIDIA wasn't on the list.
While NVIDIA currently has a Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Looking to profit from the electric vehicle mega-trend? Click the link to see our list of which EV stocks show the most long-term potential.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
