Free Trial

Technology Stocks List

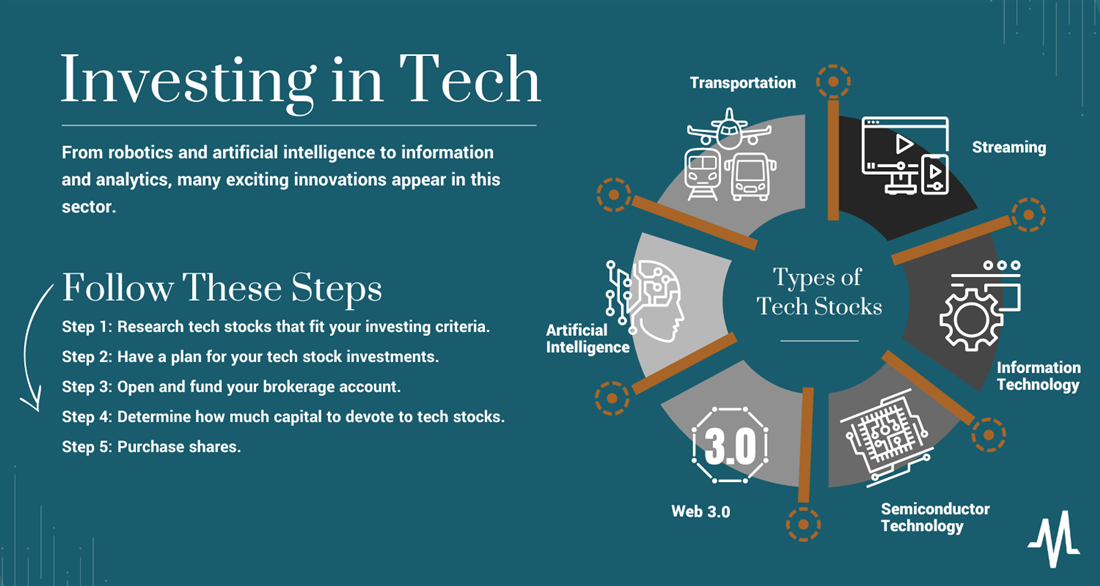
This page shows information about the 50 largest technology sector stocks including NVIDIA, Apple, Microsoft and Taiwan Semiconductor Manufacturing.

NVIDIA stock logo

1. NVIDIA NASDAQ:NVDA

$217.23 -4.07 (-1.84%)
Closing price 04:00 PM Eastern
Extended Trading
$217.06 -0.17 (-0.08%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

NVIDIA Corporation provides graphics and compute and networking solutions in the United States, Taiwan, China, Hong Kong, and internationally. More about NVIDIA

Pros of NVIDIA

  • NVidia recently reported a significant beat in its latest earnings, with revenue of $96.22 billion, which was up 105.9% year-over-year, demonstrating that the company is still growing at an explosive pace despite its massive size. This level of growth supports the current stock price of $226.32, as it indicates that the company is successfully capturing the vast majority of the artificial intelligence infrastructure market.
  • The company has announced a strategic partnership with Cisco to develop USFP optical modules that support 400Gb/s-per-lane signals and up to 12.8Tb/s of capacity. This expansion into networking technology allows NVidia to extend its reach beyond just GPUs, helping data centers scale AI systems with greater bandwidth density and power efficiency, which strengthens its position as the central platform for AI.
  • Wall Street analysts maintain a strong consensus rating of "Buy" with a consensus price target of $321.89, which is significantly higher than the current trading level. This suggests that financial professionals believe the stock is undervalued relative to its future earnings potential, particularly given that NVidia recently initiated a $150 billion stock buyback plan, signaling that the board of directors believes the shares are undervalued.

Cons of NVIDIA

  • Microsoft has announced plans to make its custom Maia chips a primary architecture for running AI models, which could reduce its dependence on NVidia GPUs. This development raises concerns about customer concentration, as major hyperscalers may increasingly rely on in-house silicon, potentially eroding NVidia's dominant market share in the data center segment.
  • There is growing concern among investors regarding the valuation of AI stocks, with some prominent figures warning that market exposure to AI has become unusually concentrated. A reported $21 million options position betting that NVidia will fall below $180 by January adds to near-term caution, suggesting that some market participants believe the current price of $226.32 may be overextended relative to fundamental value.
  • Insider selling has been significant over the past six months, with executives and directors selling shares without making corresponding purchases. For example, Director Mark A. Stevens sold over 1.2 million shares in September alone, and EVP Timothy S. Teter also sold shares. While this may reflect personal diversification, it can weigh on investor sentiment and signal that insiders may not see the current valuation as attractive for additional investment.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$5.24 trillion
P/E Ratio
27.46
Consensus Rating
Buy
Consensus Price Target
$321.89 (+48.2% Upside)
Volume
126.38 million shares
Average Volume
151.48 million shares
Today's Range
$212.85
▼
$218.47
50-Day Range
$208.48
▼
$239.24
52-Week Range
$164.27
▼
$243.37
Dividend Yield
0.44%
Apple stock logo

2. Apple NASDAQ:AAPL

$342.00 -0.96 (-0.28%)
Closing price 04:00 PM Eastern
Extended Trading
$342.27 +0.27 (+0.08%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Apple Inc designs, manufactures, and markets smartphones, personal computers, tablets, wearables, and accessories worldwide. More about Apple

Pros of Apple

  • Apple recently crossed the $5 trillion market capitalization milestone, a historic achievement that underscores its dominant position in the global technology sector and its ability to generate massive shareholder value, with the stock currently trading at $342.96.
  • The company demonstrated strong financial performance in its most recent quarter, reporting earnings per share of $2.02, which beat the consensus estimate of $1.89, while revenue grew 16.4% year-over-year to $109.42 billion, indicating robust demand and operational efficiency.
  • Apple is expanding its ecosystem into the smart home with the launch of the $299 HomeView hub and new Apple TV 4K, which features an upgraded Siri AI assistant, creating new hardware revenue streams and deepening user engagement with its services platform.

Cons of Apple

  • Apple's valuation is considered demanding with a P/E ratio of 39.33, which leaves little room for error if upcoming quarterly guidance, particularly for the December quarter, disappoints expectations, potentially leading to a stock correction.
  • Recent reports indicate that Apple has cut component orders for the iPhone 18 Pro, and some suppliers are reducing production, raising concerns about softer demand for the upcoming flagship device and potential inventory adjustments.
  • The company faces intensifying legal and competitive risks, including a trade-secrets lawsuit with OpenAI where a former employee allegedly took confidential files about an unreleased device, and competition from emerging AI platforms like Meta's Muse and Grok that could lock users into rival ecosystems.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$4.99 trillion
P/E Ratio
39.22
Consensus Rating
Moderate Buy
Consensus Price Target
$340.39 (-0.5% Downside)
Volume
39.61 million shares
Average Volume
48.56 million shares
Today's Range
$341.60
▼
$347.85
50-Day Range
$302.25
▼
$342.96
52-Week Range
$243.42
▼
$348.15
Dividend Yield
0.32%
Microsoft stock logo

3. Microsoft NASDAQ:MSFT

$539.44 +5.75 (+1.08%)
Closing price 04:00 PM Eastern
Extended Trading
$537.92 -1.53 (-0.28%)
As of 05:14 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Microsoft Corporation develops and supports software, services, devices and solutions worldwide. The Productivity and Business Processes segment offers office, exchange, SharePoint, Microsoft Teams, office 365 Security and Compliance, Microsoft viva, and Microsoft 365 copilot; and office consumer services, such as Microsoft 365 consumer subscriptions, Office licensed on-premises, and other office services. More about Microsoft

Pros of Microsoft

  • Microsoft unveiled its third-generation Maia 300 AI processor, which management claims can deliver approximately 40% more AI-generated tokens per megawatt than leading GPU-based systems, potentially improving Azure margins and reducing dependence on external chip suppliers like Nvidia.
  • The company recently reported strong financial results with revenue of $90.01 billion, beating analyst expectations, and earnings per share of $4.74, which exceeded the consensus estimate of $4.24, demonstrating robust operational performance and profitability with a net margin of 40.31%.
  • Microsoft has increased its quarterly dividend to $0.98 per share, representing a 0.7% yield and a positive change from the previous $0.91 payment, signaling continued commitment to returning capital to shareholders while maintaining a low payout ratio of 21.83%.

Cons of Microsoft

  • Corporate insiders have been selling shares, with CEO Satya Nadella and EVP Amy Hood both executing sales in September 2026 under pre-arranged trading plans, resulting in a total of 143,009 shares sold by insiders in the last three months, which may signal reduced internal confidence or personal financial planning.
  • Microsoft faces regulatory and political headwinds, as the Trump administration suspended the company from the PERM green card program, with Vice President JD Vance accusing the firm of replacing laid-off Americans with foreign workers, creating potential operational and reputational risks.
  • The company's valuation is relatively high with a price-to-earnings ratio of 30.13, which may limit upside potential if growth in Azure or AI services slows, particularly as investors await the October 28 earnings report to confirm that Azure growth remains above 40%.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$4.01 trillion
P/E Ratio
30.04
Consensus Rating
Moderate Buy
Consensus Price Target
$589.71 (+9.3% Upside)
Volume
23.48 million shares
Average Volume
34.10 million shares
Today's Range
$531.22
▼
$541.13
50-Day Range
$480.35
▼
$543.45
52-Week Range
$349.20
▼
$553.72
Dividend Yield
0.67%
Taiwan Semiconductor Manufacturing stock logo

4. Taiwan Semiconductor Manufacturing NYSE:TSM

$422.15 -7.85 (-1.83%)
Closing price 03:59 PM Eastern
Extended Trading
$422.00 -0.15 (-0.04%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Taiwan Semiconductor Manufacturing Company Limited, together with its subsidiaries, manufactures, packages, tests, and sells integrated circuits and other semiconductor devices in Taiwan, China, Europe, the Middle East, Africa, Japan, the United States, and internationally. More about Taiwan Semiconductor Manufacturing

Pros of Taiwan Semiconductor Manufacturing

  • Taiwan Semiconductor Manufacturing Company Ltd. reported record third-quarter revenue of NT$1.494 trillion, which increased 50.9% year over year and exceeded market consensus estimates by approximately 3%, demonstrating robust demand for AI accelerators and advanced chips.
  • The company is expanding its U.S. supply chain resilience through a multiyear, $2 billion agreement with GlobalFoundries to establish a U.S. supply of silicon interposers for its CoWoS packaging ecosystem, which supports long-term capacity for high-performance computing and AI customers.
  • Wall Street analysts maintain a consensus rating of Buy with an average price target of $524.89, which suggests significant upside potential from the current stock price of $457.94, reflecting confidence in the company's growth trajectory.

Cons of Taiwan Semiconductor Manufacturing

  • The stock has experienced a recent decline of 3.01% to $457.94 as investors took profits near record highs, with broader technology stocks weakening due to higher oil prices and Treasury yields pressuring growth-stock valuations.
  • Taiwan Semiconductor Manufacturing Company Ltd. carries a premium earnings multiple with a P/E ratio of 33.04, which increases the stock's sensitivity to any potential slowdown in AI spending or broader market volatility.
  • Reports indicate that the Terafab opportunity for the company is limited, as Elon Musk stated that Tesla and SpaceX intend to build and operate their planned Texas AI-chip facility themselves, reducing expectations for a major near-term role for Taiwan Semiconductor Manufacturing Company Ltd.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$2.19 trillion
P/E Ratio
30.46
Consensus Rating
Buy
Consensus Price Target
$528.22 (+25.1% Upside)
Volume
22.31 million shares
Average Volume
13.08 million shares
Today's Range
$407.13
▼
$423.66
50-Day Range
$410.11
▼
$486.04
52-Week Range
$266.82
▼
$487.47
Dividend Yield
0.78%
Broadcom stock logo

5. Broadcom NASDAQ:AVGO

$344.33 -1.92 (-0.55%)
Closing price 04:00 PM Eastern
Extended Trading
$342.54 -1.79 (-0.52%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Broadcom Inc designs, develops, and supplies various semiconductor devices with a focus on complex digital and mixed signal complementary metal oxide semiconductor based devices and analog III-V based products worldwide. More about Broadcom

Pros of Broadcom

  • Broadcom's strategy of supplying customized AI chips and networking technology to hyperscalers has reportedly secured multiyear contracts, providing strong visibility into future AI revenue without competing directly with Nvidia in general-purpose GPUs.
  • Reports indicate that Broadcom's AI revenue is tripling, reinforcing the company's strong exposure to the infrastructure spending boom, even though the stock's performance has recently lagged behind this growth.
  • The company reported a significant earnings beat in its most recent quarter, with EPS of $3.32 exceeding the consensus estimate of $3.22, and revenue of $29.59 billion, which was up 85.5% on a year-over-year basis.

Cons of Broadcom

  • Broadcom's CEO has warned that access to capital could emerge as a major constraint on the artificial intelligence boom, identifying a capital crunch as the biggest hurdle in AI-fuelled tech growth rather than memory chips.
  • The size of the $42 billion commitment to Anthropic increases execution and counterparty risk, as the company is linking its future to the success and growth of a specific AI entity.
  • Recent news regarding OpenAI's annualized revenue being lower than previously reported caused a sell-off in AI stocks, with Broadcom falling more than 4% on October 8, highlighting the volatility associated with the sector's revenue expectations.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$1.64 trillion
P/E Ratio
43.98
Consensus Rating
Moderate Buy
Consensus Price Target
$527.20 (+53.1% Upside)
Volume
28.20 million shares
Average Volume
25.00 million shares
Today's Range
$334.61
▼
$344.70
50-Day Range
$339.27
▼
$427.76
52-Week Range
$289.96
▼
$495.00
Dividend Yield
0.73%
SK hynix stock logo

6. SK hynix NASDAQ:SKHY

$146.11 -1.44 (-0.98%)
Closing price 04:00 PM Eastern
Extended Trading
$145.31 -0.80 (-0.55%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

We are one of the world’s largest memory semiconductor companies and engage in the design, manufacture and sale of advanced memory semiconductors. In the DRAM market that includes HBM, we were ranked second globally based on revenue with a market share of 29.1% in the first quarter of 2026, according to market research conducted by IDC. In the HBM market, we were ranked first globally based on revenue with a market share of 56.4% in the first quarter of 2026, according to IDC. In addition, we were the second largest supplier of NAND flash memory based on revenue, with a worldwide market share of 18.5% in the first quarter of 2026, according to IDC. Our memory products can be used in virtually all electronic devices, including graphics cards, personal computers (“PCs”), data center servers, mobile devices such as smartphones and tablets, and other consumer electronics products. We also conduct our foundry business through SK hynix system ic Inc. (“SK hynix system ic”) and SK keyfoundry Inc. (“SK keyfoundry”), our wholly-owned subsidiaries. We sell a wide variety of DRAM and NAND flash memory products with various configuration options, architectures and performance characteristics tailored to meet application- and customer-specific needs. We believe that we are one of the world’s leading companies in developing DRAMs with advanced specifications, particularly those requiring higher density, faster data-processing speed and lower power consumption. We are continually developing higher-density DRAM modules, SSDs and other advanced DRAM and NAND flash memory products that are optimized for our customers’ specific applications. In recent years, we have substantially increased our sales of HBMs. HBMs are advanced memory semiconductors designed to deliver fast data transfers while using less power, making them especially useful in high-performance applications such as GPUs, AI and high-performance computing. We have focused our sales and marketing activities in recent years on expanding our base of long-term strategic customers. We believe that our expertise and know-how in producing advanced memory semiconductors, strong long-term relationships with our key customers and state-of-the-art global production facilities in key strategic locations provide us with sustainable competitive advantages that will continue to differentiate us from our competitors and enable us to take advantage of attractive growth opportunities. We believe that we are a global leader in the HBM market with advanced production know-how and development of specific configurations that meet our customers’ demands. Our customers seek HBM suppliers with whom they can better align their own product development efforts and their strict quality standards often require HBM manufacturers to comply with rigorous testing and approval processes. We believe that our strengths in HBM, server DRAM and eSSD enable us to mitigate the risks associated with the cyclicality of the memory semiconductor market. We own and operate wafer fabrication facilities (“fabs”) in Icheon and Cheongju, Korea and Wuxi and Dalian, China. We also own and operate assembly and testing facilities for back-end processing of our products in Icheon and Cheongju, Korea and Chongqing, China. As part of our efforts to reduce unit manufacturing costs, improve manufacturing yields and enhance our profitability, we periodically phase out the operations of our older fabs or upgrade them to implement more advanced processing technologies. In addition to regular maintenance and enhancement of existing fabs, in October 2025, we opened the cleanroom of a new extension fab called “M15X” in Cheongju, which we plan to utilize to further increase our production capacity of next-generation DRAMs such as HBM. We began wafer input at the M15X in the first quarter of 2026 and expect to gradually ramp up our production volume. As part of our efforts to ensure our long-term competitiveness, we have also announced initiatives to construct an integrated industrial complex in Yongin, Korea for our next generation of fabs and research and development facilities. We began construction of our first fab at the Yongin complex in February 2025 with the phase 1 cleanroom of the first fab expected to open in the first quarter of 2027. We are currently constructing an advanced packaging plant called “P&T7” in Cheongju and expect to complete construction by the end of 2027. In December 2024, we also announced plans to build an advanced packaging plant in Indiana, United States, and expect to commence operations in the second half of 2028. In order to maintain our technological leadership, as well as to access new markets for our products, we engage in strategic initiatives, including making investments and acquisitions, from time to time. In October 2020, we agreed to acquire the NAND flash memory and storage business of Intel Corporation (“Intel”) (the “Intel NAND Business Acquisition”), including the NAND flash memory manufacturing facility in Dalian, China, NAND flash memory and SSD-related intellectual property and research and development personnel. As consideration for the Intel NAND Business Acquisition, we paid US$6.6 billion in December 2021 and US$2.2 billion in March 2025. We created a subsidiary in the United States to operate the acquired business under the brand name “Solidigm.” We also selectively acquire minority equity positions in other industry players to further strengthen our business relationships and acquire complementary businesses that we believe can further strengthen our leading position in the industry. Our principal executive offices are located in Korea.

Market Capitalization
$1.07 trillion
P/E Ratio
11.57
Consensus Rating
Buy
Consensus Price Target
$253.22 (+73.3% Upside)
Volume
33.37 million shares
Average Volume
27.04 million shares
Today's Range
$137.80
▼
$146.39
50-Day Range
$135.29
▼
$198.63
52-Week Range
$124.80
▼
$199.87
Dividend Yield
0.04%
Micron Technology stock logo

7. Micron Technology NASDAQ:MU

$931.24 +17.11 (+1.87%)
Closing price 04:00 PM Eastern
Extended Trading
$923.00 -8.24 (-0.88%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Micron Technology, Inc designs, develops, manufactures, and sells memory and storage products worldwide. The company operates through four segments: Compute and Networking Business Unit, Mobile Business Unit, Embedded Business Unit, and Storage Business Unit. More about Micron Technology

Pros of Micron Technology

  • Micron Technology, Inc. reported exceptional fiscal fourth-quarter results with revenue rising 379% year over year to $54.23 billion, significantly beating the consensus estimate of $51.33 billion, while adjusted earnings per share of $33.42 exceeded the consensus estimate of $31.77, demonstrating strong execution in the AI memory sector.
  • The company's board increased its share-repurchase authorization to approximately $35 billion, a move that signals management's confidence in long-term cash generation and provides potential support for earnings per share by reducing the number of outstanding shares.
  • Investors benefit from substantial demand visibility as more than 75% of fiscal 2027 output is reportedly committed through multi-year customer agreements, which helps stabilize pricing and margins against potential market volatility.

Cons of Micron Technology

  • China's ChangXin Memory Technologies reported progress on a denser DRAM design and plans to target server memory, raising fears that increased supply from a major competitor could weaken Micron Technology, Inc.'s pricing power in its most profitable product segments.
  • Recent insider activity has been predominantly negative, with CEO Sanjay Mehrotra selling 40,000 shares in August 2026 and EVP Sumit Sadana selling 15,000 shares, contributing to a total of 95,879 shares sold by insiders in the last three months, which may signal a lack of confidence in near-term valuation.
  • The stock has experienced a recent decline, trading down $35.85 to $953.19 on October 14, 2026, as part of a broader semiconductor sell-off driven by profit-taking and concerns about the sustainability of the current memory pricing cycle.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$1.05 trillion
P/E Ratio
12.55
Consensus Rating
Moderate Buy
Consensus Price Target
$1,407.88 (+51.2% Upside)
Volume
38.34 million shares
Average Volume
41.20 million shares
Today's Range
$858.00
▼
$931.65
50-Day Range
$861.00
▼
$1,097.39
52-Week Range
$192.40
▼
$1,255.00
Dividend Yield
0.06%
Advanced Micro Devices stock logo

8. Advanced Micro Devices NASDAQ:AMD

$562.23 -8.59 (-1.50%)
Closing price 04:00 PM Eastern
Extended Trading
$558.50 -3.73 (-0.66%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Advanced Micro Devices, Inc operates as a semiconductor company worldwide. It operates through Data Center, Client, Gaming, and Embedded segments. More about Advanced Micro Devices

Pros of Advanced Micro Devices

  • Advanced Micro Devices, Inc. recently announced an all-stock acquisition of World Labs valued at approximately $8.2 billion, a strategic move that brings in AI pioneer Fei-Fei Li and technology for generating and simulating 3D worlds, which strengthens the company's software and AI ecosystem beyond just hardware sales.
  • The company demonstrated strong financial performance in its most recent quarter, reporting revenue of $11.54 billion, which exceeded analyst expectations of $11.31 billion and represented a 50.1% year-over-year increase, indicating robust demand for its data center and client products.
  • Advanced Micro Devices, Inc. is expanding its infrastructure capabilities by providing credit support for Fermi's Texas data-center project, an arrangement that initially covers a 222-megawatt lease and extends to 650 megawatts, helping to remove power constraints that often limit the deployment of high-performance AI hardware.

Cons of Advanced Micro Devices

  • The stock carries a high valuation risk with a price-to-earnings ratio of 146.74, which is significantly elevated and leaves little room for error if earnings growth slows, making the investment vulnerable to sharp corrections if market sentiment shifts.
  • There is significant insider selling activity, with executives including CEO Lisa Su and EVP Mark Papermaster selling substantial blocks of shares in recent months, such as Lisa Su selling 70,000 shares in September 2026, which may signal that insiders are taking advantage of the high stock price to reduce their exposure.
  • Advanced Micro Devices, Inc. is exposed to broader market risks regarding the return on investment for AI infrastructure, as investors are increasingly questioning whether customers can generate sufficient profits from expensive AI hardware, a concern highlighted by recent sector-wide selloffs and concerns about AI financing costs.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$917.83 billion
P/E Ratio
144.53
Consensus Rating
Moderate Buy
Consensus Price Target
$603.51 (+7.3% Upside)
Volume
28.52 million shares
Average Volume
32.27 million shares
Today's Range
$530.09
▼
$568.62
50-Day Range
$456.16
▼
$649.42
52-Week Range
$188.22
▼
$658.52
Dividend Yield
N/A
ASML stock logo

9. ASML NASDAQ:ASML

$1,657.44 +7.44 (+0.45%)
Closing price 04:00 PM Eastern
Extended Trading
$1,650.00 -7.45 (-0.45%)
As of 05:14 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

ASML Holding N.V. develops, produces, markets, sells, and services advanced semiconductor equipment systems for chipmakers. More about ASML

Pros of ASML

  • ASML Holding reported third-quarter earnings of $14.89 per share, significantly exceeding the consensus estimate of $12.17, demonstrating strong profitability with a net margin of 30.11% and a return on equity of 52.71%.
  • The company raised its full-year 2026 revenue forecast to between $50.6 billion and $51.8 billion, surpassing the consensus estimate of $50.1 billion, and lifted its gross-margin outlook to 57.5% from 54%, indicating improved pricing power and operational efficiency.
  • Management stated that customer interest in advanced lithography systems extends through 2030, driven by AI infrastructure spending, which supports the view that the AI-related semiconductor cycle could remain strong for several years.

Cons of ASML

  • ASML Holding's production capacity limitations mean it cannot fully meet customer demand in 2027 and 2028, which could limit near-term revenue growth and delay customers' chip-production plans despite strong demand.
  • Uncertainty surrounding possible U.S. restrictions on sales of deep-ultraviolet equipment to China remains an overhang, with the company's CFO calling additional limits counterproductive, highlighting the risk that export controls could reduce access to an important market.
  • The stock experienced a 3.9% decline on Wednesday, trading as low as $1,648.80, as investors treated the earnings report as mixed due to revenue being roughly in line with expectations and capacity limitations raising questions about monetizing exceptional demand.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$651.84 billion
P/E Ratio
51.57
Consensus Rating
Moderate Buy
Consensus Price Target
$2,079.13 (+25.4% Upside)
Volume
1.97 million shares
Average Volume
1.76 million shares
Today's Range
$1,594.03
▼
$1,661.14
50-Day Range
$1,575.15
▼
$1,883.12
52-Week Range
$946.11
▼
$1,999.96
Dividend Yield
0.42%
Palantir Technologies stock logo

10. Palantir Technologies NASDAQ:PLTR

$200.50 -0.47 (-0.23%)
Closing price 04:00 PM Eastern
Extended Trading
$200.35 -0.15 (-0.07%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Palantir Technologies, Inc engages in the business of building and deploying software platforms that serve as the central operating systems for its customers. More about Palantir Technologies

Pros of Palantir Technologies

  • Palantir Technologies Inc. recently reported a significant earnings beat, delivering $0.41 in earnings per share compared to the consensus estimate of $0.34, while revenue surged 92.8% year-over-year to $1.94 billion, demonstrating strong operational momentum and the ability to exceed market expectations.
  • The stock is currently trading at $194.12, which is well above its 50-day moving average of $173.33 and 200-day moving average of $149.27, indicating a strong upward technical trend and sustained investor confidence in the company's growth trajectory.
  • Analyst sentiment has shifted positively, with the consensus rating improving to a Moderate Buy and the average price target rising to $195.33, reflecting growing institutional support and a view that the company's valuation is justified by its performance.

Cons of Palantir Technologies

  • The company trades at a premium valuation with a P/E ratio of 165.91, which is significantly higher than the software sector average, leaving little room for error if growth slows or costs rise, as highlighted by concerns from investors like Michael Burry who has taken bearish positions.
  • Insider selling has been notable, with CEO Alexander Karp selling 492,348 shares in August 2026 and other executives like Shyam Sankar and Stephen Cohen also reducing their stakes, which may signal that insiders are taking advantage of elevated stock prices to lock in gains.
  • Short interest has increased, with shares shorted rising to 60,184,903 in the most recent reporting period, indicating that a portion of the market is betting against the stock's future performance and potentially creating downward pressure on the price.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$481.81 billion
P/E Ratio
171.37
Consensus Rating
Moderate Buy
Consensus Price Target
$201.61 (+0.6% Upside)
Volume
24.68 million shares
Average Volume
42.41 million shares
Today's Range
$192.60
▼
$200.91
50-Day Range
$155.92
▼
$209.05
52-Week Range
$106.37
▼
$212.94
Dividend Yield
N/A
Intel stock logo

11. Intel NASDAQ:INTC

$95.37 -2.75 (-2.80%)
Closing price 04:00 PM Eastern
Extended Trading
$94.88 -0.49 (-0.51%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Intel Corporation designs, develops, manufactures, markets, and sells computing and related products and services worldwide. More about Intel

Pros of Intel

  • Intel Co. recently reported second-quarter revenue that increased by approximately 25% year over year, reaching $16.13 billion, which significantly exceeded the consensus estimate of $14.43 billion and demonstrated strong operational momentum and demand for its computing products.
  • The company's new 350-watt Crescent Island GPU has entered customer testing, highlighting a strategic shift toward lower-cost AI inference workloads that could appeal to enterprises seeking AI capacity without major data-center upgrades, potentially opening new revenue streams.
  • CEO Lip Bu Tan acquired 105,263 shares of Intel Co. stock at an average price of $95.00 per share in August 2026, a transaction valued at nearly $10 million, which signals strong internal confidence in the company's turnaround thesis and future performance.

Cons of Intel

  • Intel Co. continues to face significant financial pressure from its foundry business, which generated an operating loss of nearly $2.1 billion recently, consuming substantial capital and weighing on overall profitability despite revenue growth.
  • The company has a negative price-to-earnings ratio of -46.50, indicating that it is currently unprofitable on a trailing basis, which may deter value-oriented investors and reflect ongoing challenges in achieving consistent earnings stability.
  • Intel Co. stock experienced a 4.69% decline to $98.12 on October 14, 2026, amid broader semiconductor sector profit-taking and concerns about elevated valuations, higher financing costs, and intense competition from Chinese manufacturers.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$481.05 billion
P/E Ratio
N/A
Consensus Rating
Hold
Consensus Price Target
$109.06 (+14.4% Upside)
Volume
146.11 million shares
Average Volume
116.35 million shares
Today's Range
$90.02
▼
$96.87
50-Day Range
$87.26
▼
$127.39
52-Week Range
$32.89
▼
$142.35
Dividend Yield
N/A
Cisco Systems stock logo

12. Cisco Systems NASDAQ:CSCO

$109.85 -3.79 (-3.34%)
Closing price 04:00 PM Eastern
Extended Trading
$109.49 -0.36 (-0.33%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Cisco Systems, Inc designs, manufactures, and sells Internet Protocol based networking and other products related to the communications and information technology industry in the Americas, Europe, the Middle East, Africa, the Asia Pacific, Japan, and China. More about Cisco Systems

Pros of Cisco Systems

  • Cisco is currently trading at $115.34, a level that remains below the consensus analyst price target of $128.52, suggesting potential for further upside as the stock consolidates after its recent run-up from a 52-week low of $66.81.
  • The company recently announced a strategic collaboration with NVIDIA to develop ultra-dense small form factor pluggable optics, a technology designed to handle the exploding data demands of AI data centers and enable scaling of compute within the same network footprint while reducing power costs.
  • Cisco demonstrated strong financial momentum by beating consensus estimates in its latest quarterly report, delivering $1.22 in earnings per share against an expected $1.17 and generating $17.25 billion in revenue, which represented a 17.6% year-over-year increase driven by robust demand in its networking and security portfolios.

Cons of Cisco Systems

  • Valuation concerns are mounting as the stock trades at a price-to-earnings ratio of 34.53, a premium that may be difficult to justify if the recent AI-driven growth cycle is nearing its peak, leading to profit-taking and a 2.6% decline in recent trading sessions.
  • Insider selling activity has been consistent, with corporate insiders selling 44,869 shares valued at approximately $5 million over the last three months, including significant sales by the CEO and other executive vice presidents, which may signal a lack of internal conviction at current price levels.
  • Some analysts, such as HSBC, have downgraded their outlook from Buy to Hold and cut their price target to $120.00, citing fears that the company may be closer to peak growth than investors had previously assumed, creating a divergence in expert opinion.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$433.09 billion
P/E Ratio
32.89
Consensus Rating
Moderate Buy
Consensus Price Target
$128.52 (+17.0% Upside)
Volume
20.83 million shares
Average Volume
22.31 million shares
Today's Range
$108.45
▼
$112.41
50-Day Range
$106.43
▼
$123.88
52-Week Range
$68.57
▼
$130.37
Dividend Yield
1.46%
Oracle stock logo

13. Oracle NYSE:ORCL

$134.70 +4.15 (+3.18%)
Closing price 03:59 PM Eastern
Extended Trading
$133.55 -1.14 (-0.85%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Oracle Corporation offers products and services that address enterprise information technology environments worldwide. Its Oracle cloud software as a service offering include various cloud software applications, including Oracle Fusion cloud enterprise resource planning (ERP), Oracle Fusion cloud enterprise performance management, Oracle Fusion cloud supply chain and manufacturing management, Oracle Fusion cloud human capital management, Oracle Cerner healthcare, Oracle Advertising, and NetSuite applications suite, as well as Oracle Fusion Sales, Service, and Marketing. More about Oracle

Pros of Oracle

  • Oracle recently reported strong financial performance for the quarter ended September 10, 2026, beating consensus estimates with earnings per share of $1.92 compared to the expected $1.74 and revenue of $19.34 billion, which exceeded the $19.13 billion forecast, demonstrating robust demand for its cloud infrastructure and AI services.
  • The stock is currently trading at $135.35, which is significantly below the consensus price target of $251.72 set by analysts who maintain a Moderate Buy rating, suggesting substantial potential for upside recovery as the market digests recent volatility.
  • Oracle is aggressively securing renewable energy resources to support its data center expansion, including a virtual power purchase agreement for Scout Clean Energy’s 300-megawatt Ranchero Wind Farm in Texas, which helps mitigate power constraints and supports its planned investment in over 1.7 gigawatts of renewable projects.

Cons of Oracle

  • Oracle is facing significant leverage concerns as it pursues debt deals worth tens of billions of dollars to fund AI hardware, with reports indicating it is exploring financing structures where private-credit investors purchase AI chips and lease them to the company, raising risks related to financing costs and potential obsolescence of expensive chips before debt matures.
  • Operational delays at the Project Jupiter AI campus in New Mexico have forced Oracle to consider using trucks to deliver natural gas to maintain construction schedules, highlighting logistical challenges and increased costs that could delay data-center capacity coming online.
  • There are concerns that Oracle locked in fixed-margin cloud deals just before GPU prices soared, meaning the company cannot benefit from the recent sharp increases in GPU rental prices seen by competitors like CoreWeave and Nebius, potentially squeezing margins in the AI infrastructure sector.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$407.28 billion
P/E Ratio
21.11
Consensus Rating
Moderate Buy
Consensus Price Target
$251.72 (+86.9% Upside)
Volume
30.12 million shares
Average Volume
29.47 million shares
Today's Range
$127.60
▼
$135.08
50-Day Range
$130.60
▼
$162.52
52-Week Range
$114.50
▼
$322.54
Dividend Yield
1.46%
Lam Research stock logo

14. Lam Research NASDAQ:LRCX

$277.46 -9.46 (-3.30%)
Closing price 04:00 PM Eastern
Extended Trading
$276.75 -0.71 (-0.26%)
As of 05:14 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Lam Research Corporation designs, manufactures, markets, refurbishes, and services semiconductor processing equipment used in the fabrication of integrated circuits. More about Lam Research

Pros of Lam Research

  • Lam Research Co. recently reported strong financial performance for the quarter ended in July 2026, with revenue of $6.72 billion, which exceeded the consensus estimate of $6.66 billion and represented a 30.0% year-over-year increase. This significant growth in top-line revenue indicates robust demand for the company's semiconductor equipment, driven by the ongoing expansion of advanced chip manufacturing capabilities.
  • The company demonstrated strong profitability by reporting earnings per share of $1.82, beating the consensus estimate of $1.69 by $0.13. This beat, combined with a net margin of 31.27% and a return on equity of 67.60%, suggests that Lam Research Co. is efficiently converting its revenue into profit, reflecting operational excellence and a strong competitive position in the semiconductor equipment market.
  • Wall Street analysts maintain a positive outlook on the stock, with a consensus rating of "Moderate Buy" and an average price target of $364.59 as of October 2026. This target price implies significant upside potential from the current stock price of $309.56, suggesting that analysts believe the market has not yet fully priced in the company's future growth prospects and earnings potential.

Cons of Lam Research

  • The stock is currently trading at a high valuation, with a P/E ratio of 53.74 and a PEG ratio of 1.26. A P/E ratio this high means investors are paying a significant premium for each dollar of earnings, which can be risky if the company's earnings growth slows down or if market sentiment shifts, potentially leading to a significant decline in the stock price.
  • Lam Research Co. exhibits high volatility, as indicated by a beta of 1.85. A beta greater than 1.0 suggests that the stock is more volatile than the overall market, meaning it may experience larger price swings in both directions. This higher risk profile may not be suitable for investors with a low tolerance for volatility or those seeking stable, defensive investments.
  • Recent insider activity has been predominantly negative, with multiple directors and executives selling shares in the past few months. For example, Director Bethany Mayer sold 9,557 shares in September 2026, and Director Eric Brandt sold 54,500 shares in June 2026. While insider sales can be due to personal financial reasons, a pattern of selling may signal that company insiders are less confident in the stock's near-term upside or are taking advantage of the current high price levels.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$347.22 billion
P/E Ratio
48.17
Consensus Rating
Moderate Buy
Consensus Price Target
$364.59 (+31.4% Upside)
Volume
13.31 million shares
Average Volume
10.67 million shares
Today's Range
$266.12
▼
$280.45
50-Day Range
$269.23
▼
$347.49
52-Week Range
$135.50
▼
$438.50
Dividend Yield
0.44%
Applied Materials stock logo

15. Applied Materials NASDAQ:AMAT

$430.01 -16.62 (-3.72%)
Closing price 04:00 PM Eastern
Extended Trading
$428.12 -1.89 (-0.44%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Applied Materials, Inc engages in the provision of manufacturing equipment, services, and software to the semiconductor, display, and related industries. More about Applied Materials

Pros of Applied Materials

  • Applied Materials, Inc. recently unveiled a $5 billion capital investment to build the EPIC Center in Silicon Valley, which is designed to be the world's largest facility for collaborative semiconductor process technology and manufacturing equipment research and development, positioning the company to accelerate innovation for the AI era.
  • The company demonstrated strong financial performance in its most recent quarter, reporting earnings per share of $3.50, which beat the consensus estimate of $3.40, while revenue reached $9.12 billion, exceeding analyst expectations of $8.99 billion and representing a 24.8% year-over-year increase.
  • Wall Street analysts maintain a positive outlook on the stock, with a consensus rating of Moderate Buy and a consensus price target of $640.20, which suggests significant upside potential from the current stock price of $497.53.

Cons of Applied Materials

  • Despite a surge in global chip equipment spending, Applied Materials, Inc. is facing a market share test as its global equipment market share has declined from 20.0% in 2024 to 17.0%, indicating that the company is growing at a slower pace than its rivals in a rapidly expanding market.
  • The stock carries a high valuation risk with a P/E ratio of 42.89, which is significantly elevated and may leave little room for error if earnings growth slows, particularly given that the stock has recently declined 1.9% to $497.53 amid market volatility.
  • Insider selling has been notable recently, with the Chief Financial Officer selling 7,500 shares and the Chief Accounting Officer selling 725 shares in recent months, which can signal a lack of confidence from company leadership or simply a desire to diversify personal portfolios at high price points.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$341.26 billion
P/E Ratio
37.07
Consensus Rating
Moderate Buy
Consensus Price Target
$637.14 (+48.2% Upside)
Volume
12.13 million shares
Average Volume
7.89 million shares
Today's Range
$418.24
▼
$434.56
50-Day Range
$415.38
▼
$548.15
52-Week Range
$203.40
▼
$739.67
Dividend Yield
0.46%
Palo Alto Networks stock logo

16. Palo Alto Networks NASDAQ:PANW

$370.27 -4.77 (-1.27%)
Closing price 04:00 PM Eastern
Extended Trading
$371.96 +1.69 (+0.46%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Palo Alto Networks, Inc provides cybersecurity solutions worldwide. The company offers firewall appliances and software; and Panorama, a security management solution for the global control of network security platform as a virtual or a physical appliance. More about Palo Alto Networks

Pros of Palo Alto Networks

  • Strong recent financial performance with revenue growth of 34.5% year-over-year in the most recent quarter, significantly beating analyst expectations and demonstrating robust demand for the company's cybersecurity solutions.
  • Positive analyst sentiment with a consensus rating of Moderate Buy and a recent price target of $392.38, indicating that Wall Street views the stock as having significant upside potential relative to its current valuation.
  • Recent insider activity shows Director Aparna Bawa sold shares at an average price of $412.28, suggesting that even insiders are taking profits at high valuations, which may signal confidence in the stock's recent strength and high price levels.

Cons of Palo Alto Networks

  • Extremely high price-to-earnings ratio of 791.84 suggests the stock is significantly overvalued relative to its current earnings, posing a high risk of correction if growth slows or market sentiment shifts.
  • Recent insider selling by Director Aparna Bawa, who sold 250 shares on October 9, 2026, and other insiders like Josh D Paul and Dipak Golechha, may indicate that company insiders are reducing their exposure to the stock at current high prices.
  • The stock experienced a 3.6% decline on October 12, 2026, following insider selling, suggesting that recent positive momentum may be fragile and susceptible to negative news or market volatility.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$302.88 billion
P/E Ratio
726.03
Consensus Rating
Moderate Buy
Consensus Price Target
$393.02 (+6.1% Upside)
Volume
5.32 million shares
Average Volume
8.18 million shares
Today's Range
$361.68
▼
$372.05
50-Day Range
$328.48
▼
$419.91
52-Week Range
$139.57
▼
$432.33
Dividend Yield
N/A
Dell Technologies stock logo

17. Dell Technologies NYSE:DELL

$472.31 -35.62 (-7.01%)
Closing price 03:59 PM Eastern
Extended Trading
$472.00 -0.31 (-0.07%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Dell Technologies Inc designs, develops, manufactures, markets, sells, and supports various comprehensive and integrated solutions, products, and services in the Americas, Europe, the Middle East, Asia, and internationally. More about Dell Technologies

Pros of Dell Technologies

  • Dell Technologies Inc. recently reported a significant earnings beat, posting $7.04 in earnings per share for the quarter compared to the consensus estimate of $4.91, which demonstrates strong profitability and execution capability that often drives stock price appreciation.
  • The company has established itself as a major vendor of Nvidia-based servers, benefiting from the artificial intelligence infrastructure boom, with revenue for the most recent quarter reaching $46.97 billion, a 57.7% increase year-over-year, indicating robust demand for its AI-optimized hardware solutions.
  • Wall Street analysts have recently raised their price targets, with Barclays increasing its target to $603.00 and Piper Sandler to $558.00, reflecting a consensus "Moderate Buy" rating and suggesting that institutional investors believe the current valuation of $575.88 leaves room for further growth.

Cons of Dell Technologies

  • Insiders have been actively selling shares, with directors such as Silver Lake Partners and Spv-2 L.P. Sl selling hundreds of thousands of shares in recent months, which can signal a lack of confidence from those with the most knowledge of the company's internal operations.
  • The company's stock price of $575.88 is currently above the average analyst consensus price target of $571.12, suggesting that the stock may be overvalued relative to what most sell-side analysts believe it is worth, potentially limiting near-term upside.
  • Dell Technologies Inc. has a high beta of 1.37, meaning its stock price is more volatile than the overall market, which can lead to larger price swings and higher risk for investors who are sensitive to market fluctuations.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$300.30 billion
P/E Ratio
27.41
Consensus Rating
Moderate Buy
Consensus Price Target
$569.96 (+20.7% Upside)
Volume
16.31 million shares
Average Volume
8.32 million shares
Today's Range
$452.42
▼
$482.00
50-Day Range
$422.54
▼
$589.57
52-Week Range
$110.22
▼
$595.51
Dividend Yield
0.44%
SAP stock logo

18. SAP NYSE:SAP

$224.99 +4.50 (+2.04%)
Closing price 03:59 PM Eastern
Extended Trading
$224.24 -0.75 (-0.33%)
As of 05:13 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

SAP SE, together with its subsidiaries, provides applications, technology, and services worldwide. It offers SAP S/4HANA that provides software capabilities for finance, risk and project management, procurement, manufacturing, supply chain and asset management, and research and development; SAP SuccessFactors solutions for human resources, including HR and payroll, talent and employee experience management, and people and workforce analytics; and spend management solutions that covers direct and indirect spend, travel and expense, and external workforce management. More about SAP

Pros of SAP

  • SAP SE is currently trading at $218.05, which is significantly below the consensus price target of $264.57 set by twenty-one analysts, suggesting substantial upside potential for investors who believe the market is undervaluing the company's growth trajectory.
  • The company recently announced the acquisition of TechWolf, a Belgian AI work intelligence firm, to strengthen its AI-powered workforce management and skills mapping capabilities, a strategic move that aligns with the growing enterprise demand for AI-driven talent solutions.
  • SAP SE has integrated stablecoin settlement capabilities into its enterprise payment software through a partnership with Circle and Tereina, allowing businesses to pay suppliers and employees in traditional currencies or stablecoins directly from SAP software, positioning the company at the forefront of digital finance innovation.

Cons of SAP

  • SAP SE missed its earnings expectations in the most recent quarter, reporting $1.82 in earnings per share against a consensus estimate of $2.00, which may signal challenges in meeting analyst forecasts and could impact investor sentiment.
  • The company's stock price has experienced significant volatility, hitting a 52-week low of $144.97 in July 2026, indicating potential market uncertainty or concerns about the company's performance during that period.
  • Some analysts have downgraded their ratings on SAP SE, such as UBS Group cutting its rating from "buy" to "neutral" in August 2026, suggesting that not all market participants are convinced of the stock's immediate upside potential.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$276.40 billion
P/E Ratio
28.26
Consensus Rating
Moderate Buy
Consensus Price Target
$264.71 (+17.7% Upside)
Volume
2.65 million shares
Average Volume
2.97 million shares
Today's Range
$222.68
▼
$227.42
50-Day Range
$199.42
▼
$221.81
52-Week Range
$144.97
▼
$281.36
Dividend Yield
0.98%
ARM stock logo

19. ARM NASDAQ:ARM

$244.79 +6.78 (+2.85%)
Closing price 04:00 PM Eastern
Extended Trading
$243.58 -1.21 (-0.49%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Arm Holdings Plc engages in the licensing, marketing, research, and development of microprocessors, systems IP, graphics processing units, physical IP and associated systems IP, software, and tools. More about ARM

Pros of ARM

  • Arm Holdings plc demonstrated strong fundamental performance in its most recent quarter, reporting earnings per share of $0.45, which exceeded the analyst consensus estimate of $0.40 by $0.05, while revenue of $1.29 billion also surpassed expectations of $1.26 billion, indicating robust demand for its processor architectures.
  • The company is benefiting from significant growth in artificial intelligence and data-center infrastructure, as evidenced by an 11.5% monthly rebound in its stock price and a year-to-date gain of nearly 177%, driven by the fact that every major AI platform utilizes its chips and customer demand for its flagship CPU has exceeded management projections.
  • Analyst sentiment remains positive with a consensus rating of Moderate Buy and an average price target of $303.32, which is above the current stock price of $275.29, suggesting that Wall Street believes the stock is undervalued relative to its long-term potential despite recent volatility.

Cons of ARM

  • The stock is currently trading at a high valuation with a P/E ratio of 283.81 and a forward sales multiple of 43.54, which raises concerns about entry-point risks and suggests that a significant amount of future growth is already priced into the share price.
  • Arm Holdings plc is facing significant legal and financial risk from a high-stakes federal trial with Qualcomm, where billions of dollars in potential royalty payments are at stake, and the outcome could alter how the company structures its future licensing agreements and revenue streams.
  • The company exhibits extreme volatility with a beta of 3.78, meaning its stock price swings much more dramatically than the broader market, which can lead to violent price corrections during market hiccups and makes it a high-risk investment for conservative portfolios.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$261.46 billion
P/E Ratio
252.36
Consensus Rating
Moderate Buy
Consensus Price Target
$303.32 (+23.9% Upside)
Volume
6.55 million shares
Average Volume
7.61 million shares
Today's Range
$226.54
▼
$245.87
50-Day Range
$234.82
▼
$333.20
52-Week Range
$100.02
▼
$452.70
Dividend Yield
N/A
Texas Instruments stock logo

20. Texas Instruments NASDAQ:TXN

$279.12 -1.53 (-0.55%)
Closing price 04:00 PM Eastern
Extended Trading
$278.00 -1.12 (-0.40%)
As of 05:14 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Texas Instruments Incorporated designs, manufactures, and sells semiconductors to electronics designers and manufacturers in the United States and internationally. More about Texas Instruments

Pros of Texas Instruments

  • Texas Instruments Incorporated recently launched the ADC34DSO75 and LMI800PS chips, which are specifically engineered to manage power and telemetry in AI data centers, positioning the company as a critical infrastructure provider for the growing artificial intelligence hardware market.
  • The company has raised its quarterly cash dividend by 7% to $1.52 per share, marking 23 consecutive years of payout increases and offering a reliable income stream with a yield of approximately 2.1% for income-focused investors.
  • Texas Instruments Incorporated is transitioning to 300-millimeter wafer fabrication in the United States, a strategic move that significantly lowers per-chip production costs and is expected to widen free cash flow margins as capital spending normalizes.

Cons of Texas Instruments

  • The trailing price-to-earnings ratio has risen to approximately 43, which is a significant premium for a company historically viewed as a slow-growth legacy tech play, potentially limiting upside for value-conscious investors.
  • Significant insider selling occurred in the first half of 2026, including large block sales by the CEO and CFO, which may signal that company leadership is taking advantage of the recent stock price appreciation to reduce their personal exposure.
  • The dividend payout ratio is currently elevated at around 86%, leaving limited room for future dividend increases unless the anticipated expansion in free cash flow from the new manufacturing facilities materializes as projected.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$254.91 billion
P/E Ratio
42.48
Consensus Rating
Hold
Consensus Price Target
$304.26 (+9.0% Upside)
Volume
6.84 million shares
Average Volume
7.55 million shares
Today's Range
$273.59
▼
$282.51
50-Day Range
$253.34
▼
$297.23
52-Week Range
$152.73
▼
$334.03
Dividend Yield
2.02%
CrowdStrike stock logo

21. CrowdStrike NASDAQ:CRWD

$244.57 -4.72 (-1.89%)
Closing price 04:00 PM Eastern
Extended Trading
$244.00 -0.57 (-0.23%)
As of 05:14 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

CrowdStrike Holdings, Inc provides cybersecurity solutions in the United States and internationally. Its unified platform offers cloud-delivered protection of endpoints, cloud workloads, identity, and data. More about CrowdStrike

Pros of CrowdStrike

  • CrowdStrike Holdings, Inc. is currently trading at $263.01, a level that reflects strong market confidence following a recent breakout above technical resistance near $235 and a surge to a 52-week high of $286.99, indicating that institutional buyers are actively stepping in to support the stock's momentum.
  • The company reported fiscal second quarter 2027 revenue of $1.47 billion, a 25.6% year-over-year increase that exceeded consensus estimates, while adjusted earnings per share of 31 cents also beat the expected 29 cents, demonstrating that the business is generating higher profits than analysts anticipated.
  • Annual recurring revenue, which measures the predictable subscription income the company expects to collect over the next year, grew by 51% year-over-year to reach approximately $5.84 billion, driven by the rapid adoption of its Falcon Flex platform which saw a 101% increase in annual recurring revenue.

Cons of CrowdStrike

  • The stock trades at a trailing price-to-sales multiple near 45x and a forward price-to-earnings ratio around 180x, which are extremely high valuations that suggest the market has already priced in years of perfect execution and sustained growth, leaving little room for disappointment if performance slows.
  • Despite the recent rally, the average 12-month price target from 51 brokerages sits near $222.62, which is below the current trading price of $263.01, indicating that the consensus view among analysts is that the stock may be overvalued relative to its expected future earnings.
  • Management has indicated that net new annual recurring revenue additions will normalize sequentially in upcoming quarters, which could trigger periods of consolidation and cause the stock to pull back as investors adjust their expectations for the pace of growth.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$250.42 billion
P/E Ratio
6,114.25
Consensus Rating
Moderate Buy
Consensus Price Target
$236.33 (-3.4% Downside)
Volume
10.76 million shares
Average Volume
12.74 million shares
Today's Range
$239.82
▼
$246.88
50-Day Range
$185.38
▼
$278.86
52-Week Range
$85.68
▼
$286.99
Dividend Yield
N/A
Arista Networks stock logo

22. Arista Networks NYSE:ANET

$185.54 -9.89 (-5.06%)
Closing price 03:59 PM Eastern
Extended Trading
$184.98 -0.56 (-0.30%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Arista Networks, Inc engages in the development, marketing, and sale of data-driven, client to cloud networking solutions for data center, campus, and routing environments in the Americas, Europe, the Middle East, Africa, and the Asia-Pacific. More about Arista Networks

Pros of Arista Networks

  • The company demonstrated strong fundamental performance in its most recent quarter, reporting earnings per share of $1.02, which exceeded the consensus estimate of $0.89 by $0.13. This beat was accompanied by revenue of $3.04 billion, surpassing analyst expectations of $2.83 billion, indicating that the company is successfully driving growth and profitability beyond market forecasts.
  • Arista Networks, Inc. has received a consensus rating of "Moderate Buy" from research analysts, with an average price target of $235.45. This target represents a potential upside of approximately 11.7% from the current stock price of $210.72, suggesting that the financial community believes the stock is still undervalued relative to its future earnings potential.
  • The stock has shown significant momentum, trading near its 52-week high of $217.41. With a current price of $210.72, the shares are up substantially from the 52-week low of $114.52, reflecting a strong upward trend and investor confidence in the company's position in the cloud networking and AI infrastructure markets.

Cons of Arista Networks

  • Recent insider selling activity has been significant, with CEO Jayshree Ullal selling a total of 557,366 shares in early October 2026. Specifically, she sold 96,992 shares on October 7th and 460,374 shares on October 6th, transactions that may signal a lack of confidence from company leadership or simply a desire to diversify personal holdings, which can weigh on stock sentiment.
  • The stock is trading at a high valuation multiple, with a P/E ratio of 66.47. This premium valuation means that investors are paying a high price for each dollar of earnings, which can leave little room for error if future earnings growth slows or if the broader market becomes more risk-averse.
  • The company has a high beta of 1.60, indicating that its stock is significantly more volatile than the overall market. This means that Arista Networks, Inc. shares are likely to experience larger price swings in both directions, which can be risky for investors with a lower tolerance for volatility.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$234.00 billion
P/E Ratio
58.53
Consensus Rating
Moderate Buy
Consensus Price Target
$235.45 (+26.9% Upside)
Volume
10.30 million shares
Average Volume
7.88 million shares
Today's Range
$178.47
▼
$188.66
50-Day Range
$183.97
▼
$216.64
52-Week Range
$114.52
▼
$217.41
Dividend Yield
N/A
Shopify stock logo

23. Shopify NASDAQ:SHOP

$178.14 +5.64 (+3.27%)
As of 04:00 PM Eastern

Shopify Inc., a commerce company, provides a commerce platform and services in Canada, the United States, Europe, the Middle East, Africa, the Asia Pacific, Australia, China, and Latin America. The company's platform enables merchants to displays, manages, markets, and sells its products through various sales channels, including web and mobile storefronts, physical retail locations, pop-up shops, social media storefronts, native mobile apps, buy buttons, and marketplaces; and enables to manage products and inventory, process orders and payments, fulfill and ship orders, new buyers and build customer relationships, source products, leverage analytics and reporting, manage cash, payments and transactions, and access financing. It also sells custom themes and apps, and registration of domain names; and merchant solutions, which include accepting payments, shipping, and securing working capital. The company was formerly known as Jaded Pixel Technologies Inc. and changed its name to Shopify Inc. in November 2011. Shopify Inc. was incorporated in 2004 and is headquartered in Ottawa, Canada.

Market Capitalization
$229.20 billion
P/E Ratio
120.36
Consensus Rating
Moderate Buy
Consensus Price Target
$175.37 (-1.6% Downside)
Volume
10.65 million shares
Average Volume
10.35 million shares
Today's Range
$163.25
▼
$178.31
50-Day Range
$126.60
▼
$179.22
52-Week Range
$94.00
▼
$182.19
Dividend Yield
N/A
KLA stock logo

24. KLA NASDAQ:KLAC

$174.46 -4.35 (-2.43%)
Closing price 04:00 PM Eastern
Extended Trading
$173.91 -0.55 (-0.32%)
As of 05:14 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

KLA Corporation, together with its subsidiaries, engages in the design, manufacture, and marketing of process control, process-enabling, and yield management solutions for the semiconductor and related electronics industries worldwide. More about KLA

Pros of KLA

  • KLA Co. recently reported strong financial performance for the quarter ended July 28, 2026, with earnings per share of $1.05, which exceeded the consensus estimate of $1.00, and revenue of $3.66 billion, surpassing the expected $3.61 billion, demonstrating the company's ability to outperform market expectations and drive shareholder value through robust operational execution.
  • The company has received significant institutional support, with Quintet Private Bank Europe S.A. increasing its position in KLA Co. by 212.9% in the third quarter to hold 175,162 shares, and Colton Groome Financial Advisors LLC raising its stake by 40.1%, indicating growing confidence among professional investors in the long-term trajectory of the semiconductor equipment sector.
  • Analyst sentiment remains positive with a consensus rating of Moderate Buy and an average price target of $221.26, which suggests potential upside from the current stock price of $196.72, as recent upgrades from firms like Stifel Nicolaus and Sanford C. Bernstein reflect optimism about the company's future earnings growth and market position.

Cons of KLA

  • There is significant insider selling activity, with CEO Richard P. Wallace selling 72,019 shares in September 2026 and other executives like Brian Lorig and Mary Beth Wilkinson also reducing their holdings, which may signal that company insiders are taking advantage of current valuations to lock in gains, potentially indicating a lack of confidence in further short-term price appreciation.
  • The stock is trading at a premium valuation with a P/E ratio of 53.65, which is high relative to many industrial peers, suggesting that investors are paying a substantial amount for each dollar of earnings, and this high multiple leaves little room for error if future earnings growth slows or if the broader semiconductor sector faces a cyclical downturn.
  • Short interest in KLA Co. has been notable, with 23,554,039 shares shorted as of the September 15, 2026 record date, representing a short percentage of float that indicates a portion of the market is betting against the stock's performance, which can create downward pressure on the share price if these positions are not covered.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$227.67 billion
P/E Ratio
47.58
Consensus Rating
Moderate Buy
Consensus Price Target
$221.26 (+26.8% Upside)
Volume
13.69 million shares
Average Volume
11.09 million shares
Today's Range
$168.42
▼
$175.43
50-Day Range
$167.36
▼
$209.37
52-Week Range
$107.20
▼
$307.37
Dividend Yield
0.50%
International Business Machines stock logo

25. International Business Machines NYSE:IBM

$234.04 +6.16 (+2.70%)
Closing price 03:59 PM Eastern
Extended Trading
$233.75 -0.29 (-0.13%)
As of 05:12 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

International Business Machines Corporation, together with its subsidiaries, provides integrated solutions and services worldwide. More about International Business Machines

Pros of International Business Machines

  • International Business Machines Co. has advanced to Stage C, the final phase of the Defense Advanced Research Projects Agency's Quantum Benchmarking Initiative, which provides independent government validation of its hardware and architecture as it pursues a fault-tolerant quantum computer by 2029, strengthening its technical credibility and long-term value proposition.
  • The stock is currently trading at $226.70, which is significantly below its fifty-two week high of $332.46, making the valuation more attractive for investors who believe in a recovery of consulting demand and hybrid cloud services, as the price-to-earnings ratio of 20.12 suggests a reasonable entry point relative to its earnings power.
  • International Business Machines Co. offers a dividend yield of 3.05%, providing a steady income stream for investors, with a recent quarterly dividend of $1.69 per share paid in September 2026, which represents a $6.76 annualized payout and a payout ratio of 59.98% that is sustainable given the company's financial health.

Cons of International Business Machines

  • Recent operating concerns remain unresolved, as the company previously disclosed that numerous large deals failed to close on time, contributing to a quarterly revenue shortfall in the second quarter of 2026 where actual revenue of $17.16 billion missed analyst estimates of $17.46 billion, raising fears that a prolonged slowdown could pressure earnings and investor confidence.
  • International Business Machines Co. is experiencing customer leakage in its infrastructure market, evidenced by 11:11 Systems acquiring select IBM VMware Cloud Service Provider enterprise customers, which suggests competitive pressure and potential loss of business volume in a key segment of its hybrid cloud and infrastructure offerings.
  • The stock has underperformed the broader market over the past three months, losing 26% while the S&P 500 gained 4.8%, indicating that investors are skeptical about the company's ability to execute on its strategy and deliver consistent growth, which could lead to further downside if upcoming earnings do not show improvement.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$220.50 billion
P/E Ratio
20.77
Consensus Rating
Moderate Buy
Consensus Price Target
$254.96 (+8.9% Upside)
Volume
5.59 million shares
Average Volume
7.47 million shares
Today's Range
$226.01
▼
$234.14
50-Day Range
$220.14
▼
$249.09
52-Week Range
$199.19
▼
$332.46
Dividend Yield
2.93%
Marvell Technology stock logo

26. Marvell Technology NASDAQ:MRVL

$241.24 -4.04 (-1.65%)
Closing price 04:00 PM Eastern
Extended Trading
$239.36 -1.89 (-0.78%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Marvell Technology, Inc, together with its subsidiaries, provides data infrastructure semiconductor solutions, spanning the data center core to network edge. More about Marvell Technology

Pros of Marvell Technology

  • Marvell Technology, Inc. recently raised its fiscal 2028 revenue target to approximately $20 billion, which exceeds the Wall Street consensus of roughly $18.2 billion, signaling strong confidence in future growth from custom silicon and data-center infrastructure demand.
  • The company is benefiting from significant acceleration in custom AI silicon, including the Microsoft Maia 300 program, while its connectivity and optics businesses, such as the new 3.2T protocol-aware retimer, are already contributing to revenue growth in high-bandwidth AI data centers.
  • Analyst sentiment remains positive with a consensus rating of Moderate Buy and a target price of $320.82, which is significantly higher than the current stock price of $245.28, suggesting substantial upside potential for investors.

Cons of Marvell Technology

  • The stock trades at a premium valuation with a P/E ratio of 80.95, which is high relative to many peers, meaning investors are paying a significant price for expected growth that may not materialize if execution falters.
  • Shares have experienced a sharp decline of 8.7% in recent trading, falling to $245.28, driven by a broad AI-chip selloff and caution ahead of inflation data, indicating high volatility and sensitivity to macroeconomic factors.
  • Recent insider selling, including transactions by the COO and CAO, has added to near-term sentiment pressure and raised concerns about profit-taking following the stock's exceptionally strong run in 2026.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$211.54 billion
P/E Ratio
79.62
Consensus Rating
Moderate Buy
Consensus Price Target
$327.36 (+35.7% Upside)
Volume
23.61 million shares
Average Volume
27.54 million shares
Today's Range
$227.31
▼
$242.55
50-Day Range
$206.48
▼
$287.01
52-Week Range
$70.68
▼
$329.88
Dividend Yield
0.09%
Salesforce stock logo

27. Salesforce NYSE:CRM

$246.66 +10.71 (+4.54%)
Closing price 03:59 PM Eastern
Extended Trading
$242.54 -4.12 (-1.67%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Salesforce, Inc provides Customer Relationship Management (CRM) technology that brings companies and customers together worldwide. More about Salesforce

Pros of Salesforce

  • Salesforce, Inc. recently received a rare double upgrade from Bank of America to a Buy rating with a price target of $285, which is significantly higher than the current stock price of $235.95, suggesting substantial upside potential as analysts argue that AI should deepen customer dependence on the company's platform.
  • The company demonstrated strong financial performance in its most recent quarter, reporting earnings per share of $5.90, which significantly beat the consensus estimate of $3.27, while revenue of $11.35 billion also exceeded expectations, indicating robust demand and operational efficiency.
  • Salesforce, Inc. is actively strengthening its artificial intelligence capabilities through strategic acquisitions, such as the purchase of AI-powered analytics platform Loops, and expanded partnerships with DocuSign to integrate intelligent agreement management natively into its Agentforce and Slack ecosystems.

Cons of Salesforce

  • There is growing investor skepticism regarding the financial impact of agentic AI, with market participants demanding clearer evidence that AI adoption will materially increase revenue and margins rather than cannibalizing existing software spending, which is contributing to recent stock weakness.
  • Despite strong earnings, the stock has underperformed the broader market, losing 3.8% over the past twelve months compared to the S&P 500's 17.3% return, suggesting that the market is not fully rewarding the company's performance relative to its peers.
  • Short interest in Salesforce, Inc. has increased significantly, with shares shorted rising to 32.89 million as of September 30, 2026, representing a 1.67% month-over-month increase and indicating that a notable portion of traders are betting against the stock's future price appreciation.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$203.00 billion
P/E Ratio
22.49
Consensus Rating
Moderate Buy
Consensus Price Target
$278.12 (+12.8% Upside)
Volume
8.72 million shares
Average Volume
13.58 million shares
Today's Range
$238.02
▼
$247.18
50-Day Range
$186.96
▼
$264.13
52-Week Range
$146.32
▼
$269.11
Dividend Yield
0.75%
Sandisk stock logo

28. Sandisk NASDAQ:SNDK

$1,394.83 -8.51 (-0.61%)
Closing price 04:00 PM Eastern
Extended Trading
$1,374.01 -20.82 (-1.49%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

SanDisk Corporation offers flash storage solutions. The Company designs, develops and manufactures data storage solutions in a range of form factors using flash memory, controller, firmware and software technologies. The Company operates through flash memory storage products segment. Its solutions include a range of solid state drives (SSD), embedded products, removable cards, universal serial bus (USB), drives, wireless media drives, digital media players, and wafers and components. It offers SSDs for client computing applications, which encompass desktop computers, notebook computers, tablets and other computing devices. Its embedded products are used for embedded storage for mobile phones, tablets, notebooks and other portable and wearable devices, as well as in automotive and connected home applications. Its removable products include cards, USB flash drives, Wireless Drives and Digital Media Players at a range of storage capacities. It sells memory wafers and memory components.

Market Capitalization
$201.59 billion
P/E Ratio
19.13
Consensus Rating
Moderate Buy
Consensus Price Target
$2,120.65 (+52.0% Upside)
Volume
13.13 million shares
Average Volume
15.12 million shares
Today's Range
$1,276.00
▼
$1,397.64
50-Day Range
$1,212.21
▼
$1,887.04
52-Week Range
$136.29
▼
$2,354.39
Dividend Yield
N/A
Amphenol stock logo

29. Amphenol NYSE:APH

$81.51 -1.18 (-1.43%)
Closing price 03:59 PM Eastern
Extended Trading
$80.81 -0.70 (-0.86%)
As of 05:07 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Amphenol Corporation, together with its subsidiaries, primarily designs, manufactures, and markets electrical, electronic, and fiber optic connectors in the United States, China, and internationally. More about Amphenol

Pros of Amphenol

  • Amphenol Co. recently crossed above its 200-day moving average of $76.69, a technical indicator that often signals a shift from a long-term downtrend to an uptrend, suggesting that recent buying pressure is strong enough to overcome previous selling pressure and potentially drive further price appreciation.
  • The company demonstrated exceptional earnings momentum by beating consensus estimates in its most recent quarterly report, posting earnings per share of $0.68 against an expected $0.60 and generating revenue of $8.76 billion, which significantly exceeded the $8.26 billion consensus, indicating that the firm is successfully converting its strategic initiatives into tangible financial results.
  • Amphenol Co. is benefiting from surging demand in the artificial intelligence infrastructure sector, as its connectors and interconnect systems are critical components for high-speed data transmission in data centers, allowing the company to capture growth from the broader AI boom without being limited to a single chip maker or cloud provider.

Cons of Amphenol

  • The stock is trading at a premium valuation with a P/E ratio of 41.40, which is significantly higher than the broader market average, meaning investors are paying a high price for each dollar of earnings, and any disappointment in future growth could lead to a sharp correction in the share price.
  • Recent insider activity has been dominated by selling, with the CEO and CFO both executing large block sales in the last few months, such as the CFO selling 386,400 shares and the CEO selling over 1.3 million shares in July, which can signal that company leadership is taking advantage of high stock prices to reduce their personal exposure.
  • Short interest in the stock has increased substantially, with shares shorted rising to over 30 million in the most recent reporting period, a 132% increase from the previous month, indicating that a significant portion of the market is betting against the stock's future performance and expecting a decline.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$201.00 billion
P/E Ratio
40.86
Consensus Rating
Moderate Buy
Consensus Price Target
$98.56 (+20.9% Upside)
Volume
15.62 million shares
Average Volume
17.28 million shares
Today's Range
$78.37
▼
$81.73
50-Day Range
$76.55
▼
$88.59
52-Week Range
$59.01
▼
$89.93
Dividend Yield
0.58%
Analog Devices stock logo

30. Analog Devices NASDAQ:ADI

$403.95 +0.38 (+0.09%)
Closing price 04:00 PM Eastern
Extended Trading
$401.53 -2.42 (-0.60%)
As of 05:11 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Analog Devices, Inc designs, manufactures, tests, and markets integrated circuits (ICs), software, and subsystems products in the United States, rest of North and South America, Europe, Japan, China, and rest of Asia. More about Analog Devices

Pros of Analog Devices

  • Strong recent financial performance with revenue up 39.2% year over year in the latest quarter, beating consensus estimates and demonstrating robust demand for the company's semiconductor products.
  • Consensus analyst ratings have shifted to a Buy stance with a price target of approximately $458, which is significantly higher than the current stock price of $405.93, suggesting potential upside for investors.
  • Strategic partnerships such as the collaboration with Moët Hennessy and UC Davis on AI-enabled chemical-signature detection for wine production highlight the company's ability to apply its technology in diverse and innovative industries.

Cons of Analog Devices

  • Recent insider selling by key executives, including the CFO and CEO, under pre-arranged trading plans may signal a lack of confidence in the stock's near-term performance or a desire to diversify personal holdings.
  • The company's price-to-earnings ratio of 48.15 is relatively high, which could make the stock vulnerable to profit-taking if growth slows or if the broader market sentiment shifts negatively.
  • Short interest has been increasing, with the percentage of shares shorted rising to 1.79% of the float, indicating that some investors are betting against the stock's future performance.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$195.74 billion
P/E Ratio
47.92
Consensus Rating
Moderate Buy
Consensus Price Target
$460.09 (+13.9% Upside)
Volume
4.57 million shares
Average Volume
4.03 million shares
Today's Range
$394.18
▼
$410.00
50-Day Range
$354.52
▼
$420.55
52-Week Range
$223.47
▼
$445.91
Dividend Yield
1.08%
Qualcomm stock logo

31. Qualcomm NASDAQ:QCOM

$178.40 +5.78 (+3.35%)
Closing price 04:00 PM Eastern
Extended Trading
$177.45 -0.95 (-0.53%)
As of 05:14 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Qualcomm Incorporated engages in the development and commercialization of foundational technologies for the wireless industry worldwide. More about Qualcomm

Pros of Qualcomm

  • QUALCOMM Incorporated shares are currently trading at $172.62, which is significantly below the average analyst price target of $204.10, suggesting potential upside for investors who believe the market is undervaluing the company's long-term prospects.
  • A Delaware federal jury recently ruled that Arm Holdings breached its licensing agreement with QUALCOMM Incorporated, confirming the company's right to continue developing custom Oryon CPUs, which strengthens its strategic flexibility and reduces legal risks associated with its CPU roadmap and relationship with Meta Platforms.
  • QUALCOMM Incorporated reported revenue of $9.95 billion for the most recent quarter, which exceeded analyst estimates of $9.69 billion, demonstrating the company's ability to generate strong top-line growth despite challenges in the smartphone market.

Cons of Qualcomm

  • QUALCOMM Incorporated remains heavily dependent on smartphone chips, which generated approximately $5.1 billion or more than half of its quarterly revenue, exposing the company to significant risk if handset demand continues to decline or if customers shift to competitors.
  • Investors appear skeptical of QUALCOMM Incorporated's "AI" repositioning, viewing the company as caught between a pressured smartphone business and unproven growth in AI and data-center chips, which is weighing on the broader investment narrative and contributing to a consensus "Hold" rating from analysts.
  • The stock is trading below its 50-day moving average of $174.28 and its 200-day moving average of $178.72, signaling weak near-term momentum and potential downward pressure on the share price in the coming months.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$190.50 billion
P/E Ratio
20.65
Consensus Rating
Hold
Consensus Price Target
$204.10 (+14.4% Upside)
Volume
11.76 million shares
Average Volume
15.28 million shares
Today's Range
$168.84
▼
$179.21
50-Day Range
$158.53
▼
$201.97
52-Week Range
$121.99
▼
$259.92
Dividend Yield
2.08%
Seagate Technology stock logo

32. Seagate Technology NASDAQ:STX

$690.81 -22.73 (-3.19%)
Closing price 04:00 PM Eastern
Extended Trading
$684.22 -6.59 (-0.95%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Seagate Technology Holdings plc provides data storage technology and solutions in Singapore, the United States, the Netherlands, and internationally. It provides mass capacity storage products, including enterprise nearline hard disk drives (HDDs), enterprise nearline solid state drives (SSDs), enterprise nearline systems, video and image HDDs, and network-attached storage drives. The company also offers legacy applications comprising Mission Critical HDDs and SSDs; external storage solutions under the Seagate Ultra Touch, One Touch, and Expansion product lines, as well as under the LaCie brand name; desktop drives; notebook drives, DVR HDDs, and gaming SSDs. In addition, it provides Lyve edge-to-cloud mass capacity platform. The company sells its products primarily to OEMs, distributors, and retailers. Seagate Technology Holdings plc was founded in 1978 and is based in Dublin, Ireland.

Market Capitalization
$157.08 billion
P/E Ratio
49.77
Consensus Rating
Moderate Buy
Consensus Price Target
$986.00 (+42.7% Upside)
Volume
5.86 million shares
Average Volume
4.39 million shares
Today's Range
$652.29
▼
$691.99
50-Day Range
$713.54
▼
$994.79
52-Week Range
$209.00
▼
$1,145.00
Dividend Yield
0.40%
ServiceNow stock logo

33. ServiceNow NYSE:NOW

$148.86 +8.88 (+6.35%)
Closing price 03:59 PM Eastern
Extended Trading
$147.78 -1.08 (-0.73%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

ServiceNow, Inc provides end to-end intelligent workflow automation platform solutions for digital businesses in the North America, Europe, the Middle East and Africa, Asia Pacific, and internationally. More about ServiceNow

Pros of ServiceNow

  • ServiceNow, Inc. shares are currently trading at $139.92, a level that sits below the consensus price target of $146.46, suggesting potential for near-term price appreciation as analysts like Argus recently raised their target to $170.00 with a buy rating.
  • The company demonstrated strong fundamental performance in its most recent quarter, reporting revenue of $3.99 billion which exceeded analyst expectations of $3.93 billion, while earnings per share of $0.90 also beat the consensus estimate of $0.86, indicating robust demand for its platform.
  • ServiceNow, Inc. is successfully expanding its artificial intelligence capabilities, evidenced by the City of Raleigh using its AI agents to reduce IT service-desk costs by 66%, which provides a concrete example of productivity gains that could drive broader public-sector and enterprise adoption.

Cons of ServiceNow

  • The stock carries a high valuation with a P/E ratio of 87.45, which leaves less room for disappointment and makes the shares vulnerable to price corrections if growth slows or if competitors gain market share in the AI sector.
  • Insider selling has been notable in recent months, with insiders selling 14,081 shares worth approximately $1.94 million in the last ninety days, including significant sales by Director Paul Chamberlain and insider Jacqueline P. Canney, which may signal a lack of confidence from those closest to the company.
  • ServiceNow, Inc. faces intense competition in the artificial intelligence space, as highlighted by Zacks, which notes that despite long-term adoption opportunities, the stock's premium earnings multiple makes it particularly sensitive to competitive pressures and valuation concerns.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$153.92 billion
P/E Ratio
93.04
Consensus Rating
Moderate Buy
Consensus Price Target
$150.88 (+1.4% Upside)
Volume
17.59 million shares
Average Volume
21.63 million shares
Today's Range
$139.58
▼
$149.34
50-Day Range
$117.31
▼
$148.43
52-Week Range
$81.24
▼
$192.97
Dividend Yield
N/A
Accenture stock logo

34. Accenture NYSE:ACN

$224.84 +9.88 (+4.60%)
Closing price 03:59 PM Eastern
Extended Trading
$225.47 +0.63 (+0.28%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Accenture plc, a professional services company, provides strategy and consulting, industry X, song, and technology and operation services worldwide. More about Accenture

Pros of Accenture

  • Accenture recently reported fourth-quarter earnings that exceeded analyst expectations, posting earnings per share of $3.29 against a consensus estimate of $3.18 and generating revenue of $18.68 billion, which surpassed the projected $18.03 billion. This strong performance, combined with a 6.2% year-over-year revenue increase, demonstrates the company's ability to deliver consistent growth and profitability, which is a key driver for stock price appreciation.
  • The stock is currently trading at $214.86, a level that reflects a significant recovery from its fifty-two-week low of $118.15. This price point sits well above the fifty-day simple moving average of $184.52 and the 200-day simple moving average of $173.50, indicating strong short-term momentum and technical strength that often attracts further institutional buying.
  • Accenture has initiated a $2.00 billion share repurchase program, which allows the company to buy back up to 2.4% of its outstanding shares. Share buybacks are typically a sign that company leadership believes the stock is undervalued, and reducing the number of shares in circulation can increase the earnings per share for remaining shareholders, thereby boosting the stock's value.

Cons of Accenture

  • Despite the recent earnings beat, the consensus rating from eleven investment analysts is "Hold," with fourteen analysts assigning a Hold rating and two issuing a Sell rating. This mixed sentiment suggests that while the company is performing well, many experts believe the stock may not have significant upside potential from its current levels, leading to a cautious outlook.
  • Company insiders have been actively selling their shares, with COO Catherine Hogan selling 1,320 shares and General Counsel Joel Unruch selling 10,498 shares in recent transactions. While these sales were executed under pre-arranged trading plans, a pattern of insider selling can sometimes signal that executives believe the stock is overvalued or that they are diversifying their personal wealth, which may weigh on investor confidence.
  • The stock has experienced significant volatility, having fallen from a fifty-two-week high of $291.09 to a low of $118.15 before recovering. This wide range indicates high risk and uncertainty in the market's perception of the company's value, which can lead to substantial losses for investors who buy at the wrong time or who are unable to withstand large price swings.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$150.15 billion
P/E Ratio
16.58
Consensus Rating
Hold
Consensus Price Target
$219.26 (-2.5% Downside)
Volume
8.45 million shares
Average Volume
7.00 million shares
Today's Range
$216.27
▼
$227.86
50-Day Range
$170.23
▼
$214.86
52-Week Range
$118.15
▼
$291.09
Dividend Yield
3.03%
Fortinet stock logo

35. Fortinet NASDAQ:FTNT

$181.91 -2.14 (-1.16%)
Closing price 04:00 PM Eastern
Extended Trading
$181.50 -0.41 (-0.23%)
As of 05:12 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Fortinet, Inc provides cybersecurity and convergence of networking and security solutions worldwide. It offers secure networking solutions focus on the convergence of networking and security; network firewall solutions that consist of FortiGate data centers, hyperscale, and distributed firewalls, as well as encrypted applications; wireless LAN solutions; and secure connectivity solutions, including FortiSwitch secure ethernet switches, FortiAP wireless local area network access points, FortiExtender 5G connectivity gateways, and other products. More about Fortinet

Pros of Fortinet

  • Fortinet, Inc. recently reported strong financial results for the quarter ended July 29, 2026, with earnings per share of $0.90, which exceeded the analyst consensus estimate of $0.75 by $0.15, and revenue of $2.05 billion, surpassing the consensus estimate of $1.89 billion, demonstrating robust demand for its cybersecurity solutions.
  • The company has set ambitious guidance for the full year 2026, projecting earnings per share between $3.41 and $3.47, which is significantly higher than the consensus estimate of $3.08, and revenue between $8.0 billion and $8.2 billion, indicating management confidence in continued growth and operational efficiency.
  • Fortinet, Inc. is benefiting from the expanding AI cybersecurity market, as highlighted by recent positive sentiment from Motley Fool and Zacks, which cite the company's role in protecting physical AI infrastructure and its status as a strong momentum stock with potential for further earnings beats.

Cons of Fortinet

  • The consensus price target for Fortinet, Inc. is $152.79, which is significantly below the current stock price of $189.10, suggesting that analysts believe the stock is overvalued and may face downward pressure if growth or cash generation slows.
  • Fortinet, Inc. has a high P/E ratio of 66.58, which is elevated compared to many other software companies, and investors are questioning whether the company's future cash flow can justify this valuation, especially after a multiyear rally that has returned about 224.4% over the past three years.
  • Insiders have been selling shares of Fortinet, Inc., with CEO Ken Xie selling 161,482 shares and VP Michael Xie selling 3,121 shares in August 2026, and COO John Whittle selling 56,700 shares in September 2026, which could signal a lack of confidence in the stock's near-term performance.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$133.47 billion
P/E Ratio
64.05
Consensus Rating
Hold
Consensus Price Target
$159.09 (-12.5% Downside)
Volume
3.74 million shares
Average Volume
5.84 million shares
Today's Range
$178.27
▼
$183.07
50-Day Range
$150.79
▼
$194.75
52-Week Range
$73.55
▼
$197.13
Dividend Yield
N/A
Western Digital stock logo

36. Western Digital NASDAQ:WDC

$356.45 -7.65 (-2.10%)
Closing price 04:00 PM Eastern
Extended Trading
$352.12 -4.33 (-1.22%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Western Digital Corporation develops, manufactures, and sells data storage devices and solutions in the United States, China, Hong Kong, Europe, the Middle East, Africa, rest of Asia, and internationally. It offers client devices, including hard disk drives (HDDs) and solid state drives (SSDs) for desktop and notebook personal computers (PCs), gaming consoles, and set top boxes; and flash-based embedded storage products for mobile phones, tablets, notebook PCs, and other portable and wearable devices, as well as automotive, Internet of Things, industrial, and connected home applications. The company also provides enterprise HDDs; enterprise SSDs consisting of flash-based SSDs and software solutions for use in enterprise servers, online transactions, data analysis, and other enterprise applications; and data storage platforms. In addition, it offers external HDD storage products in mobile and desktop form; client portable SSDs; removable cards that are used in consumer devices comprising mobile phones, tablets, imaging systems, and cameras and smart video systems; universal serial bus flash drives for use in the computing and consumer markets; and wireless drive products used in-field backup of created content, as well as wireless streaming of high-definition movies, photos, music, and documents to tablets, smartphones, and PCs. The company sells its products under the Western Digital, SanDisk, and WD brands to original equipment manufacturers, distributors, dealers, resellers, and retailers. Western Digital Corporation was founded in 1970 and is headquartered in San Jose, California.

Market Capitalization
$133.43 billion
P/E Ratio
14.72
Consensus Rating
Moderate Buy
Consensus Price Target
$618.63 (+73.6% Upside)
Volume
12.18 million shares
Average Volume
8.65 million shares
Today's Range
$336.00
▼
$356.83
50-Day Range
$364.10
▼
$536.01
52-Week Range
$117.23
▼
$799.87
Dividend Yield
0.16%
Corning stock logo

37. Corning NYSE:GLW

$138.32 -2.58 (-1.83%)
Closing price 03:59 PM Eastern
Extended Trading
$137.85 -0.46 (-0.33%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Corning Incorporated engages in the display technologies, optical communications, environmental technologies, specialty materials, and life sciences businesses in the United States and internationally. More about Corning

Pros of Corning

  • Corning Incorporated is positioned to benefit significantly from the artificial intelligence boom, as rising demand for data centers and communications infrastructure drives growth in its optical fiber and cable segments, with analysts highlighting rising backlogs and potential for further gains as network investment accelerates.
  • The company recently secured a major $3 billion fiber deal with AT&T, which signals strong corporate confidence in Corning's ability to meet the surging demand for high-capacity network infrastructure required to support AI workloads and data center expansion.
  • Corning Incorporated demonstrated strong financial performance in its most recent quarter, reporting earnings per share of $0.78, which beat analyst consensus estimates of $0.76, while revenue of $4.74 billion exceeded expectations and grew 17.1% year-over-year, indicating robust operational execution.

Cons of Corning

  • Corning Incorporated is currently facing a securities investigation by Pomerantz LLP on behalf of investors, which creates legal uncertainty and potential reputational pressure that could weigh on the stock price in the near term, even though no wrongdoing has been established.
  • The stock has experienced significant volatility and a sharp decline recently, trading down 6.4% to $152.81, and is currently trading below its 200-day simple moving average of $168.44, suggesting a potential downtrend or correction phase following its strong year-to-date performance.
  • Valuation concerns are emerging after a 93% surge year-to-date, with a price-to-earnings ratio of 69.78, which some analysts argue is elevated and may limit additional upside potential if profit execution does not continue to accelerate at the same pace.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$119.14 billion
P/E Ratio
63.16
Consensus Rating
Moderate Buy
Consensus Price Target
$177.56 (+28.4% Upside)
Volume
11.26 million shares
Average Volume
11.98 million shares
Today's Range
$132.75
▼
$138.65
50-Day Range
$140.89
▼
$173.29
52-Week Range
$77.39
▼
$271.78
Dividend Yield
0.76%
Snowflake stock logo

38. Snowflake NYSE:SNOW

$335.81 +0.73 (+0.22%)
Closing price 03:59 PM Eastern
Extended Trading
$335.64 -0.17 (-0.05%)
As of 05:14 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Snowflake Inc provides a cloud-based data platform for various organizations in the United States and internationally. Its platform offers Data Cloud, which enables customers to consolidate data into a single source of truth to drive meaningful business insights, build data-driven applications, and share data and data products, as well as applies artificial intelligence (AI) for solving business problems. More about Snowflake

Pros of Snowflake

  • Snowflake Inc. demonstrated strong fundamental momentum by beating consensus estimates in its most recent quarter, reporting earnings per share of $0.62 against an expected $0.45 and revenue of $1.55 billion, which exceeded the $1.48 billion forecast. This performance highlights the company's ability to drive 35.1% year-over-year revenue growth, signaling robust demand for its cloud-based data platform among enterprise clients.
  • The stock is currently trading at $359.85, which remains significantly below the consensus price target of $414.24 held by analysts who maintain a "Moderate Buy" rating. This valuation gap suggests that the market may not yet fully price in the company's growth trajectory, offering potential upside for investors who believe in the long-term expansion of the AI Data Cloud sector.
  • Snowflake Inc. is strategically positioning itself for the future of artificial intelligence by appointing Jeff Naughton, a prominent database scientist, as a Technical Fellow to advance data systems for the agentic enterprise. This move reinforces the company's commitment to building infrastructure that supports AI agents, a key driver of new enterprise workloads and potential revenue streams.

Cons of Snowflake

  • Snowflake Inc. continues to operate with negative GAAP profitability, reporting a GAAP EPS of -$0.55 in the most recent quarter and a negative net margin of 20.07%. This indicates that the company is still spending more than it is earning on a generally accepted accounting principles basis, which may limit its ability to generate consistent cash flows for shareholders in the near term.
  • Valuation concerns are mounting as the stock has rallied 68% year-to-date, stretching its price-to-earnings ratio to -113.16. Analysts have noted that expectations are rising faster than earnings, creating a risk that the current price may be overextended relative to the company's actual financial performance, making it vulnerable to profit-taking.
  • Insider selling activity has been significant, with executives and directors selling over 1.2 million shares valued at approximately $396 million in the last 90 days. Notable sales include EVP Christian Kleinerman and Director Frank Slootman, which may signal that company insiders are taking advantage of the recent stock price appreciation to reduce their personal exposure.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$118.47 billion
P/E Ratio
N/A
Consensus Rating
Moderate Buy
Consensus Price Target
$414.24 (+23.4% Upside)
Volume
5.68 million shares
Average Volume
6.49 million shares
Today's Range
$317.82
▼
$336.38
50-Day Range
$307.31
▼
$368.35
52-Week Range
$118.30
▼
$384.56
Dividend Yield
N/A
Cloudflare stock logo

39. Cloudflare NYSE:NET

$314.76 -9.57 (-2.95%)
Closing price 03:59 PM Eastern
Extended Trading
$316.92 +2.16 (+0.69%)
As of 05:14 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Cloudflare, Inc operates as a cloud services provider that delivers a range of services to businesses worldwide. The company provides an integrated cloud-based security solution to secure a range of combination of platforms, including public cloud, private cloud, on-premise, software-as-a-service applications, and IoT devices; and website and application security products comprising web application firewall, bot management, distributed denial of service, API gateways, SSL/TLS encryption, script management, security center, and rate limiting products. More about Cloudflare

Pros of Cloudflare

  • Cloudflare, Inc. recently reported strong financial performance for the second quarter of 2026, with revenue of $696.06 million, which exceeded analyst expectations of $664.66 million and represented a 35.9% year-over-year increase, demonstrating robust demand for its services.
  • The company has received significant positive momentum from Wall Street, with BTIG Research raising its price target to $413.00 and issuing a Buy rating, while the consensus rating remains a Moderate Buy with an average price target of $326.33, suggesting potential upside from the current stock price of $342.19.
  • Strategic partnerships are expanding the company's reach, including a deal with Deutsche Telekom that aims to enhance European enterprise distribution and create new opportunities for security and connectivity growth.

Cons of Cloudflare

  • Despite strong revenue growth, Cloudflare, Inc. continues to report negative net profitability, with a negative net margin of 8.21% and a negative return on equity of 3.88% in the most recent quarter, indicating ongoing challenges in achieving consistent profitability.
  • The stock trades at a premium valuation, with a price-to-earnings ratio of -589.99, which may limit upside potential and increase the risk of a significant correction if growth expectations are not met.
  • Recent insider selling activity is notable, with CEO Matthew Prince selling all of his shares in early August 2026 and CFO Thomas J. Seifert selling 10,000 shares in September 2026, which could signal a lack of confidence from company leadership.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$111.26 billion
P/E Ratio
N/A
Consensus Rating
Moderate Buy
Consensus Price Target
$330.59 (+5.0% Upside)
Volume
4.49 million shares
Average Volume
4.06 million shares
Today's Range
$305.01
▼
$317.24
50-Day Range
$272.64
▼
$360.32
52-Week Range
$158.83
▼
$370.35
Dividend Yield
N/A
Adobe stock logo

40. Adobe NASDAQ:ADBE

$251.67 +10.99 (+4.57%)
Closing price 04:00 PM Eastern
Extended Trading
$250.08 -1.59 (-0.63%)
As of 05:14 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Adobe Inc, together with its subsidiaries, operates as a diversified software company worldwide. It operates through three segments: Digital Media, Digital Experience, and Publishing and Advertising. More about Adobe

Pros of Adobe

  • Adobe's stock is currently trading at $238.14, which represents a significant discount to the consensus price target of $282.68, suggesting substantial upside potential for investors who believe the recent sell-off has been an overreaction to temporary market fears.
  • The company demonstrated strong fundamental performance in its most recent quarter, reporting earnings per share of $6.13, which beat analyst estimates of $6.08, while also raising its full-year 2026 guidance to $24.45-$24.50, indicating management confidence in continued growth despite market volatility.
  • Adobe maintains a highly profitable business model with a net margin of 28.05% and a return on equity of 65.65%, metrics that reflect its ability to generate substantial cash flow from its subscription-based Digital Media and Digital Experience segments.

Cons of Adobe

  • Wells Fargo recently downgraded Adobe to Underweight and cut its price target to $225, citing concerns that the company is losing budget share to competitors as CIOs shift spending toward other AI software offerings, which could pressure future revenue growth.
  • Analysts have raised concerns about "meaningful cracks" in Adobe's organic growth, noting that the company may need to nearly double its new recurring revenue to meet its targets, suggesting that the current growth rate may not be sustainable without significant new product adoption.
  • The stock has experienced significant volatility and a decline of approximately 30% this year, underperforming many of its enterprise software peers, which may indicate broader market skepticism about Adobe's long-term competitive position in the AI era.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$97.95 billion
P/E Ratio
14.04
Consensus Rating
Hold
Consensus Price Target
$283.90 (+12.8% Upside)
Volume
6.59 million shares
Average Volume
5.72 million shares
Today's Range
$243.44
▼
$254.32
50-Day Range
$231.01
▼
$292.79
52-Week Range
$190.12
▼
$363.70
Dividend Yield
N/A
Datadog stock logo

41. Datadog NASDAQ:DDOG

$266.25 -3.08 (-1.14%)
Closing price 04:00 PM Eastern
Extended Trading
$264.70 -1.55 (-0.58%)
As of 05:12 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Datadog, Inc operates an observability and security platform for cloud applications in North America and internationally. More about Datadog

Pros of Datadog

  • The company demonstrated strong fundamental performance in its most recent quarter, reporting revenue of $1.12 billion which exceeded analyst estimates of $1.08 billion and represented a 35.6% year-over-year increase. This growth was accompanied by an earnings per share of $0.65, beating the consensus estimate of $0.58, indicating that the company is not only expanding its customer base but also improving its profitability efficiency.
  • Wall Street sentiment has shifted significantly in favor of the stock, with the consensus price target rising to $277.73 as of October 7, 2026. This target is above the current stock price of $271.34, suggesting that analysts believe the stock is still undervalued relative to its future earnings potential. Recent upgrades from major firms like Wells Fargo and Barclays, which raised their targets to $295.00 and $290.00 respectively, reflect confidence in the company's ability to sustain its high-growth trajectory.
  • Institutional investors are actively increasing their exposure to the company, signaling strong confidence in its long-term value. For instance, Cooper Financial Group increased its holdings by 188.1% in the third quarter, and MassMutual Private Wealth & Trust FSB acquired a new position of 92,844 shares. This trend of institutional accumulation, where large funds are buying more shares, often indicates that professional investors see significant upside potential in the stock.

Cons of Datadog

  • The stock is trading at a very high valuation, with a price-to-earnings ratio of 553.77 as of October 7, 2026. This means that investors are paying a significant premium for each dollar of earnings, which can be risky if the company fails to meet its high growth expectations. A high P/E ratio often leaves little room for error, as any disappointment in earnings or guidance could lead to a sharp decline in the stock price.
  • There has been significant insider selling activity, with company executives selling a total of 958,076 shares valued at $232,038,673 in the last ninety days. For example, CFO David Obstler sold 40,000 shares in September, and CTO Alexis Le-Quoc sold 53,912 shares in August. While these sales were executed under pre-arranged trading plans, the volume of insider selling can be a bearish signal, as insiders are often in the best position to know the company's true value and may be taking advantage of the high stock price to reduce their exposure.
  • The company's growth rate is expected to slow down, with revenue growth projected to decrease from 36% to around 29% in the third quarter. This deceleration in growth could be a concern for investors who are paying a premium for high-growth stocks. If the company cannot maintain its rapid growth pace, it may face pressure to cut costs or reduce investments, which could impact its ability to innovate and compete in the fast-evolving technology landscape.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$95.60 billion
P/E Ratio
543.38
Consensus Rating
Moderate Buy
Consensus Price Target
$281.18 (+5.6% Upside)
Volume
2.82 million shares
Average Volume
5.16 million shares
Today's Range
$256.22
▼
$266.91
50-Day Range
$209.23
▼
$293.26
52-Week Range
$98.01
▼
$300.68
Dividend Yield
N/A
ASE Technology stock logo

42. ASE Technology NYSE:ASX

$41.98 -2.35 (-5.31%)
Closing price 03:59 PM Eastern
Extended Trading
$41.87 -0.10 (-0.24%)
As of 05:13 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

ASE Technology Holding Co, Ltd., together with its subsidiaries, provides semiconductors packaging and testing, and electronic manufacturing services in the United States, Taiwan, Asia, Europe, and internationally. More about ASE Technology

Pros of ASE Technology

  • ASE Technology Holding Co., Ltd. is currently trading at $44.39, a level that reflects significant recent momentum as the stock has quadrupled in value over the past year, reaching a 52-week high of $47.93 in early October 2026.
  • The company reported a 46% year-over-year increase in September 2026 net revenues, driven by strong demand in its core Assembly, Testing, and Material division, which signals accelerating growth in its primary business segment.
  • ASE Technology Holding Co., Ltd. recently expanded its PowerSiP platform for next-generation AI power delivery, positioning the company to benefit from the expanding market for advanced semiconductor packaging required by artificial intelligence hardware.

Cons of ASE Technology

  • The stock carries a high price-to-earnings ratio of 51.62, which is significantly elevated and suggests that the current valuation may be stretched relative to its earnings, increasing the risk of a correction if growth slows.
  • ASE Technology Holding Co., Ltd. has a beta of 1.66, indicating that the stock is more volatile than the broader market and may experience sharper price swings during periods of market uncertainty.
  • Several institutional investors, including Legacy Wealth Asset Management LLC, reduced their stakes in the company during the third quarter of 2026, with Legacy Wealth cutting its position by 21.2%, which may signal a lack of confidence among some large holders.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$93.83 billion
P/E Ratio
48.81
Consensus Rating
Buy
Consensus Price Target
N/A
Volume
11.36 million shares
Average Volume
8.53 million shares
Today's Range
$40.64
▼
$42.14
50-Day Range
$35.73
▼
$47.62
52-Week Range
$12.31
▼
$47.93
Dividend Yield
0.63%
AppLovin stock logo

43. AppLovin NASDAQ:APP

$279.29 +17.10 (+6.52%)
Closing price 04:00 PM Eastern
Extended Trading
$278.23 -1.07 (-0.38%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

AppLovin Corporation engages in building a software-based platform for advertisers to enhance the marketing and monetization of their content in the United States and internationally. It operates through two segments, Software Platform and Apps. The company's software solutions include AppDiscovery, a marketing software solution, which matches advertiser demand with publisher supply through auctions; MAX, an in-app bidding software that optimizes the value of a publisher's advertising inventory by running a real-time competitive auction; Adjust, a measurement and analytics marketing platform that provides marketers with the visibility, insights, and tools needed to grow their apps from early stage to maturity; and Wurl, a connected TV platform, which distributes streaming video for content companies and provides advertising and publishing solutions through its AdPool, ContentDiscovery, and Global FAST Pass products. It also offers SparkLabs, which uses app store optimization to enhance ad visibility; AppLovin Exchange, which connects buyers to mobile and CTV devices through a single and direct RTB exchange; and Array, an end-to-end app management suite for mobile operators and end users. In addition, the company operates various free-to-play mobile games. It serves individuals, small and independent businesses, enterprises, advertisers and advertising networks, mobile app publishers, indie studio developers, and internet platforms. AppLovin Corporation was incorporated in 2011 and is headquartered in Palo Alto, California.

Market Capitalization
$93.46 billion
P/E Ratio
21.47
Consensus Rating
Moderate Buy
Consensus Price Target
$511.32 (+83.1% Upside)
Volume
4.37 million shares
Average Volume
5.60 million shares
Today's Range
$260.59
▼
$280.25
50-Day Range
$262.19
▼
$346.80
52-Week Range
$260.59
▼
$738.01
Dividend Yield
N/A
Synopsys stock logo

44. Synopsys NASDAQ:SNPS

$468.11 -11.82 (-2.46%)
Closing price 04:00 PM Eastern
Extended Trading
$467.98 -0.13 (-0.03%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Synopsys, Inc provides electronic design automation software products used to design and test integrated circuits. It operates in three segments: Design Automation, Design IP, and Software Integrity. More about Synopsys

Pros of Synopsys

  • Synopsys, Inc. has secured new AI chip-design alliances with OpenAI and Amazon, which reinforce its position as a key supplier of software used to design advanced AI semiconductors, with the expanded Amazon relationship described as a potential $1 billion opportunity.
  • The company's board of directors authorized a $1 billion share-repurchase program on October 5th, which permits the repurchase of up to 1.1% of its shares, a move that generally signals management believes the stock is undervalued and can support earnings per share.
  • Wall Street analysts maintain a consensus rating of Moderate Buy with an average price target of $584.11, which is significantly higher than the current stock price of $502.67, suggesting potential for further upside.

Cons of Synopsys

  • CFO Sudhindra Kankanwadi sold a combined 12,170 shares for roughly $6.0 million across October 5 and 6, reducing his direct holdings by about 40%, which may weigh on investor sentiment after the recent rally.
  • The stock trades at a demanding valuation with a price-to-earnings ratio of 88.81 and a price-to-earnings-growth ratio of 1.99, raising questions about whether the AI exposure justifies the premium relative to other software stocks.
  • Market analysis notes that Synopsys shares have declined after several recent earnings beats, suggesting that investor expectations are unusually high and that strong results may already be priced into the stock.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$89.71 billion
P/E Ratio
82.71
Consensus Rating
Moderate Buy
Consensus Price Target
$571.78 (+22.1% Upside)
Volume
3.17 million shares
Average Volume
2.06 million shares
Today's Range
$454.49
▼
$472.17
50-Day Range
$367.70
▼
$509.99
52-Week Range
$362.55
▼
$539.48
Dividend Yield
N/A
Cadence Design Systems stock logo

45. Cadence Design Systems NASDAQ:CDNS

$324.38 -5.08 (-1.54%)
Closing price 04:00 PM Eastern
Extended Trading
$323.25 -1.13 (-0.35%)
As of 05:14 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Cadence Design Systems, Inc provides software, hardware, services, and reusable integrated circuit (IC) design blocks worldwide. More about Cadence Design Systems

Pros of Cadence Design Systems

  • Cadence Design Systems, Inc. recently reported strong financial performance for the quarter ended July 27, 2026, with revenue of $1.58 billion, which represented a 24.2% increase compared to the same period last year, indicating robust demand for its electronic design automation software and hardware solutions.
  • The company demonstrated consistent ability to exceed market expectations, as it reported earnings per share of $2.11 for the most recent quarter, beating the consensus estimate of $2.05 by $0.06, which suggests strong operational efficiency and profitability with a net margin of 23.60%.
  • Analysts maintain a positive outlook on the stock, with a consensus rating of Moderate Buy and a consensus price target of $405.06, which is significantly higher than the current stock price of $348.84, implying potential upside for investors.

Cons of Cadence Design Systems

  • The stock is currently trading at a high valuation with a price-to-earnings ratio of 69.35, which may limit upside potential if future earnings growth does not meet the elevated expectations embedded in the current price of $348.84.
  • Insider selling activity has been notable, with multiple executives and directors, including CEO Anirudh Devgan and CFO John M Wall, selling significant numbers of shares in recent months, which could signal a lack of confidence in the stock's near-term performance.
  • Some analysts have recently downgraded their ratings on the stock, such as Weiss Ratings downgrading from hold (c+) to hold (c) and Wall Street Zen downgrading from buy to hold, indicating concerns about the company's valuation or competitive position.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$89.33 billion
P/E Ratio
64.49
Consensus Rating
Moderate Buy
Consensus Price Target
$404.14 (+24.6% Upside)
Volume
2.58 million shares
Average Volume
2.45 million shares
Today's Range
$315.91
▼
$328.05
50-Day Range
$273.96
▼
$359.55
52-Week Range
$262.75
▼
$416.69
Dividend Yield
N/A
Intuit stock logo

46. Intuit NASDAQ:INTU

$330.17 +19.73 (+6.36%)
Closing price 04:00 PM Eastern
Extended Trading
$329.40 -0.78 (-0.23%)
As of 05:13 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Intuit Inc provides financial management and compliance products and services for consumers, small businesses, self-employed, and accounting professionals in the United States, Canada, and internationally. More about Intuit

Pros of Intuit

  • Intuit Inc. recently reported strong financial performance for the quarter ended August 25, 2026, beating consensus estimates with earnings per share of $4.03 compared to the expected $3.58 and revenue of $4.35 billion against an estimate of $4.27 billion, demonstrating robust top-line growth of 13.7% year-over-year and a net margin of 21.29%.
  • The company is expanding its AI capabilities through the Accountant Suite, which is gaining adoption among accounting professionals by offering AI-powered and agentic workflows that integrate with QuickBooks, payroll, and marketing analytics, potentially increasing customer engagement and strengthening the broader Intuit ecosystem.
  • Intuit Inc. has increased its quarterly dividend to $1.38 per share, payable on October 16, 2026, representing a significant boost from the previous $1.20 payout and resulting in an annualized dividend yield of approximately 1.82% based on the current stock price of $305.99.

Cons of Intuit

  • The stock is currently trading at $305.99, which is significantly below its 50-day simple moving average of $322.04 and 200-day simple moving average of $332.76, indicating that the stock is in a technical downtrend and trading below key long-term support levels.
  • Analysts have downgraded their outlook on the stock, with Bank of America cutting its rating from "buy" to "neutral" and setting a price target of $360.00, while the overall consensus rating has shifted to "Hold" with an average price target of $431.55, reflecting concerns about slowing customer additions and premium valuation.
  • Short interest in Intuit Inc. has increased significantly, with shares shorted rising to 7,277,607 as of September 30, 2026, up from 7,016,125 in the previous month, suggesting that a growing number of traders are betting against the stock's future performance.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$88.23 billion
P/E Ratio
20.01
Consensus Rating
Hold
Consensus Price Target
$431.55 (+30.7% Upside)
Volume
4.50 million shares
Average Volume
4.27 million shares
Today's Range
$314.00
▼
$332.27
50-Day Range
$268.03
▼
$369.92
52-Week Range
$252.84
▼
$689.17
Dividend Yield
1.83%
Lumentum stock logo

47. Lumentum NASDAQ:LITE

$869.54 -26.79 (-2.99%)
Closing price 04:00 PM Eastern
Extended Trading
$868.90 -0.63 (-0.07%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Lumentum Holdings Inc. manufactures and sells optical and photonic products in the Americas, the Asia-Pacific, Europe, the Middle East, and Africa. The company operates through two segments: Optical Communications (OpComms) and Commercial Lasers (Lasers). The OpComms segment offers components, modules, and subsystems that enable the transmission and transport of video, audio, and data over high-capacity fiber optic cables. It offers tunable transponders, transceivers, and transmitter modules; tunable lasers, receivers, and modulators; transport products, such as reconfigurable optical add/drop multiplexers, amplifiers, and optical channel monitors, as well as components, including 980nm, multi-mode, and Raman pumps; and switches, attenuators, photodetectors, gain flattening filters, isolators, wavelength-division multiplexing filters, arrayed waveguide gratings, multiplex/de-multiplexers, and integrated passive modules. This segment also provides Super Transport Blade, which integrates optical transport functions into a single-slot blade; vertical-cavity surface-emitting lasers; directly modulated and electro-absorption modulated lasers; and laser illumination sources for 3D sensing systems. It serves customers in telecommunications, data communications, and consumer and industrial markets. The Commercial Lasers segment offers diode-pumped solid-state, fiber, diode, direct-diode, and gas lasers, such as argon-ion and helium-neon lasers for use in original equipment manufacturer applications. It serves customers in markets and applications, such as sheet metal processing, general manufacturing, biotechnology, solar cell processing, graphics and imaging, remote sensing, and precision machining. Lumentum Holdings Inc. was incorporated in 2015 and is headquartered in San Jose, California.

Market Capitalization
$78.77 billion
P/E Ratio
N/A
Consensus Rating
Moderate Buy
Consensus Price Target
$1,078.75 (+24.1% Upside)
Volume
7.56 million shares
Average Volume
5.50 million shares
Today's Range
$800.00
▼
$874.73
50-Day Range
$813.51
▼
$1,133.40
52-Week Range
$152.54
▼
$1,143.00
Dividend Yield
N/A
Hewlett Packard Enterprise stock logo

48. Hewlett Packard Enterprise NYSE:HPE

$58.71 -4.40 (-6.97%)
Closing price 03:59 PM Eastern
Extended Trading
$58.36 -0.35 (-0.60%)
As of 05:15 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Hewlett Packard Enterprise Company provides solutions that allow customers to capture, analyze, and act upon data seamlessly in the Americas, Europe, the Middle East, Africa, the Asia Pacific, and Japan. More about Hewlett Packard Enterprise

Pros of Hewlett Packard Enterprise

  • Strong earnings momentum is evident as the company reported $1.11 in earnings per share for the most recent quarter, significantly beating the consensus estimate of $0.93, while revenue grew 33.7% year-over-year to $12.21 billion, indicating robust demand for its AI infrastructure solutions.
  • The stock has experienced a substantial rally, with the current price at $70.26 representing a significant increase from the 52-week low of $19.84, reflecting a 197% gain over the past six months as the market revalues the company as a fast-growing AI infrastructure player rather than just a hardware vendor.
  • Recent strategic partnerships, such as the collaboration with NVIDIA to strengthen enterprise AI offerings and the selection of the HPE Cray XD2000 system by Mizuho Securities for advanced financial simulations, demonstrate the company's expanding footprint in high-performance computing and AI-ready infrastructure.

Cons of Hewlett Packard Enterprise

  • Valuation concerns are emerging as the stock trades at a P/E ratio of 36.59, which some analysts argue is steep for a hardware maker, and the current price of $70.26 is above the average analyst price target of $65.78, suggesting the stock may be overextended relative to consensus expectations.
  • Significant insider selling activity has been observed, with CEO Antonio Neri selling 250,000 shares in October and 250,000 shares in September, and EVP Rami Rahim selling 34,456 shares, totaling over $35 million in insider sales over the last ninety days, which may signal a lack of confidence from company leadership at current price levels.
  • The stock has experienced recent volatility, including a 4.4% drop on Monday to $70.26 and a previous gap down of 6.48% in September, indicating that the rapid rally has been accompanied by sharp corrections and heightened sensitivity to market sentiment or analyst downgrades, such as the recent downgrade by Evercore to "In Line."
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$77.94 billion
P/E Ratio
30.58
Consensus Rating
Moderate Buy
Consensus Price Target
$65.44 (+11.5% Upside)
Volume
34.76 million shares
Average Volume
21.36 million shares
Today's Range
$56.64
▼
$60.20
50-Day Range
$50.85
▼
$73.50
52-Week Range
$19.84
▼
$73.56
Dividend Yield
0.81%
Motorola Solutions stock logo

49. Motorola Solutions NYSE:MSI

$456.65 +4.92 (+1.09%)
Closing price 03:59 PM Eastern
Extended Trading
$454.79 -1.86 (-0.41%)
As of 05:12 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

Motorola Solutions, Inc provides public safety and enterprise security solutions in the United States, the United Kingdom, Canada, and internationally. More about Motorola Solutions

Pros of Motorola Solutions

  • Motorola Solutions, Inc. recently expanded its counter-drone security capabilities through a $1.5 billion acquisition of D-Fend, which adds the EnforceAir platform to its portfolio. This strategic move strengthens the company's position in the public safety and enterprise security sectors by broadening its reach into advanced aerial threat detection and mitigation, potentially driving new revenue streams and enhancing its competitive advantage against rivals like Axon.
  • The company demonstrated strong financial performance in its most recent quarterly report, posting earnings per share of $4.41, which significantly beat the analyst consensus estimate of $3.85. This beat, combined with revenue of $3.13 billion that exceeded expectations of $3 billion, indicates robust demand for its communications and video security solutions, supporting a narrative of resilient growth and operational efficiency.
  • Investors can benefit from the current stock price of $450.95, which is trading below the average analyst price target of $519.56. This valuation gap suggests potential upside as the market digests the company's recent acquisitions and strong order backlog, which reached a record $15.6 billion, indicating sustained customer demand and future revenue visibility.

Cons of Motorola Solutions

  • Recent insider activity shows significant selling pressure, with CEO Gregory Q. Brown selling 14,220 shares in September 2026 and SVP Kathryn Moore selling 1,004 shares in August 2026. These transactions, which reduced their respective holdings by 17.58% and 43.92%, may signal that company executives are taking advantage of higher stock prices to liquidate positions, potentially indicating a lack of confidence in further near-term appreciation.
  • Motorola Solutions, Inc. carries a high debt-to-equity ratio of 3.13, which indicates a significant level of leverage relative to its equity base. While the company has a current ratio of 1.10, the high debt load could limit its financial flexibility in a rising interest rate environment or during economic downturns, potentially increasing financial risk and constraining its ability to fund future acquisitions or R&D without additional borrowing.
  • The company's P/E ratio of 35.51 is relatively high compared to many industrial and technology peers, suggesting that the stock is priced for perfection. This valuation leaves little room for error if future earnings growth slows or if the market becomes more risk-averse, as any disappointment in quarterly results could lead to a significant multiple compression and stock price decline.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$75.57 billion
P/E Ratio
35.96
Consensus Rating
Buy
Consensus Price Target
$530.10 (+16.1% Upside)
Volume
799,286 shares
Average Volume
1.05 million shares
Today's Range
$455.21
▼
$461.68
50-Day Range
$444.08
▼
$491.54
52-Week Range
$359.36
▼
$494.85
Dividend Yield
1.08%
TE Connectivity stock logo

50. TE Connectivity NYSE:TEL

$212.89 +2.64 (+1.26%)
Closing price 03:59 PM Eastern
Extended Trading
$213.54 +0.65 (+0.30%)
As of 04:36 PM Eastern
Extended trading is trading that happens on electronic markets outside of regular trading hours. This is a fair market value extended hours price provided by Massive. Learn more.

TE Connectivity Ltd., together with its subsidiaries, manufactures and sells connectivity and sensor solutions in Europe, the Middle East, Africa, the AsiaPacific, and the Americas. More about TE Connectivity

Pros of TE Connectivity

  • TE Connectivity Ltd. recently demonstrated strong financial performance by beating analyst expectations in its most recent earnings report, delivering earnings per share of $2.94 against a consensus estimate of $2.85, while also exceeding revenue forecasts with $5.16 billion in sales compared to the expected $5.01 billion, indicating robust demand for its connectivity and sensor solutions.
  • The company has set optimistic guidance for the fourth quarter of 2026, projecting earnings per share of $3.05 and revenue of $5.3 billion, which signals continued growth momentum and suggests that the business is well-positioned to maintain its upward trajectory in the coming months.
  • Wall Street analysts maintain a positive outlook on the stock, with a consensus rating of Moderate Buy and an average price target of $252.36, which represents significant upside potential from the current stock price of $216.97, reflecting confidence in the company's long-term value proposition.

Cons of TE Connectivity

  • Recent insider activity shows a pattern of selling, with Shadrak W Kroeger selling 9,400 shares in June 2026 and other executives like John S Jenkins and Heath A Mitts also reducing their holdings in late 2025 and early 2026, which may signal a lack of confidence from those with the most intimate knowledge of the company's operations.
  • Short interest in TE Connectivity Ltd. has been increasing, with shares shorted rising to 7,313,620 as of September 30, 2026, up from 5,745,623 in February 2026, suggesting that a growing number of traders are betting against the stock's future performance.
  • The stock has experienced volatility, including a gap down of 9.68% on July 22, 2026, and another gap down of 26.4% on April 22, 2026, indicating that the stock is susceptible to sharp declines and may carry higher risk for investors seeking stability.
A.I. GeneratedThese insights were generated using artificial intelligence. They are based on proprietary MarketBeat data, news articles, and custom LLM A.I. algorithms.
Market Capitalization
$61.63 billion
P/E Ratio
20.87
Consensus Rating
Moderate Buy
Consensus Price Target
$258.07 (+21.2% Upside)
Volume
3.01 million shares
Average Volume
2.35 million shares
Today's Range
$207.31
▼
$212.99
50-Day Range
$200.29
▼
$220.21
52-Week Range
$190.27
▼
$252.56
Dividend Yield
1.44%