HubSpot (NYSE:HUBS - Get Free Report) was downgraded by analysts at JPMorgan Chase & Co. from an "overweight" rating to a "neutral" rating in a research report issued on Thursday, Marketbeat reports. They currently have a $240.00 target price on the software maker's stock. JPMorgan Chase & Co.'s price objective points to a potential upside of 8.86% from the company's current price.
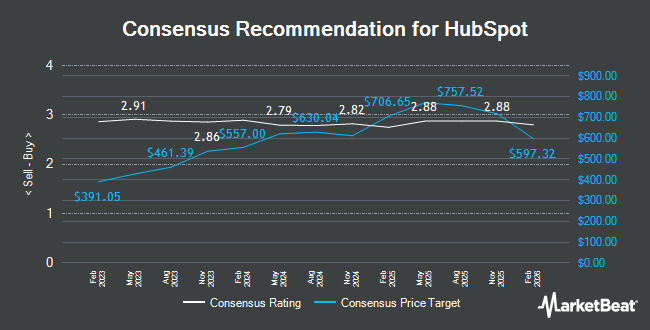
A number of other equities research analysts also recently commented on HUBS. Wolfe Research downgraded shares of HubSpot from an "outperform" rating to a "peer perform" rating in a report on Thursday, August 6th. Canaccord Genuity Group reduced their target price on shares of HubSpot from $335.00 to $300.00 and set a "buy" rating on the stock in a report on Thursday, August 6th. BTIG Research reissued a "buy" rating and issued a $250.00 price objective on shares of HubSpot in a research report on Friday, September 18th. Zacks Research lowered HubSpot from a "strong-buy" rating to a "hold" rating in a report on Wednesday, August 12th. Finally, Royal Bank Of Canada reiterated an "outperform" rating on shares of HubSpot in a research report on Tuesday. Thirteen investment analysts have rated the stock with a Buy rating, nineteen have assigned a Hold rating and two have given a Sell rating to the company's stock. According to data from MarketBeat.com, the stock has an average rating of "Hold" and a consensus price target of $264.65.
View Our Latest Analysis on HUBS
HubSpot Stock Performance
HUBS opened at $220.46 on Thursday. HubSpot has a one year low of $169.63 and a one year high of $497.96. The business's fifty day moving average is $230.54 and its two-hundred day moving average is $218.43. The company has a market cap of $10.99 billion, a price-to-earnings ratio of 77.90, a PEG ratio of 2.26 and a beta of 1.24.
HubSpot (NYSE:HUBS - Get Free Report) last posted its earnings results on Wednesday, August 5th. The software maker reported $3.26 earnings per share for the quarter, beating the consensus estimate of $3.02 by $0.24. HubSpot had a net margin of 4.26% and a return on equity of 8.66%. The firm had revenue of $911.74 million during the quarter, compared to the consensus estimate of $898.31 million. During the same period last year, the firm posted $2.19 EPS. The firm's revenue for the quarter was up 19.8% on a year-over-year basis. HubSpot has set its FY 2026 guidance at 13.230-13.310 EPS and its Q3 2026 guidance at 3.250-3.270 EPS. On average, analysts predict that HubSpot will post 4.59 EPS for the current fiscal year.
Insider Buying and Selling
In other HubSpot news, insider Erika Fisher sold 702 shares of the business's stock in a transaction dated Tuesday, August 4th. The stock was sold at an average price of $235.22, for a total transaction of $165,124.44. Following the sale, the insider owned 14,581 shares in the company, valued at approximately $3,429,742.82. The trade was a 4.59% decrease in their position. The transaction was disclosed in a filing with the Securities & Exchange Commission, which is accessible through this hyperlink. Also, Director Brian Halligan sold 8,500 shares of the business's stock in a transaction that occurred on Tuesday, July 21st. The shares were sold at an average price of $221.09, for a total transaction of $1,879,265.00. Following the sale, the director owned 85,000 shares in the company, valued at $18,792,650. This represents a 9.09% decrease in their position. The disclosure for this sale is available in the SEC filing. In the last quarter, insiders have sold 26,202 shares of company stock valued at $5,998,079. 3.70% of the stock is owned by corporate insiders.
Hedge Funds Weigh In On HubSpot
Institutional investors and hedge funds have recently modified their holdings of the stock. Elevation Wealth Partners LLC grew its stake in HubSpot by 66.7% in the third quarter. Elevation Wealth Partners LLC now owns 175 shares of the software maker's stock valued at $36,000 after purchasing an additional 70 shares in the last quarter. Reflection Asset Management acquired a new stake in shares of HubSpot in the fourth quarter valued at about $37,000. Global Retirement Partners LLC acquired a new position in shares of HubSpot during the second quarter worth approximately $38,000. CX Institutional raised its stake in HubSpot by 4,785.7% during the 2nd quarter. CX Institutional now owns 342 shares of the software maker's stock valued at $62,000 after purchasing an additional 335 shares during the last quarter. Finally, Oslo Pensjonsforsikring AS bought a new stake in shares of HubSpot in the first quarter valued at about $74,000. 90.39% of the stock is currently owned by hedge funds and other institutional investors.
HubSpot News Roundup
Here are the key news stories impacting HubSpot this week:
- Positive Sentiment: HubSpot is eliminating approximately 660 positions, or 7% of its workforce, as part of a restructuring intended to streamline operations and support AI-focused offerings. Management reaffirmed its third-quarter and full-year 2026 outlook, suggesting the cuts are not currently forcing a reduction in expected results. The company expects $65 million to $75 million in restructuring charges, primarily in the fourth quarter, while potential longer-term cost savings could support margins. HubSpot reaffirms 2026 guidance as it cuts about 7% of workforce
- Positive Sentiment: Needham & Company reaffirmed its “buy” rating and assigned a $300 price target, implying substantial upside from the stock’s recent level. Zacks also highlighted HubSpot as a strong growth stock, supported by its recurring-revenue business and continued expansion. Here's Why HubSpot is a Strong Growth Stock
- Neutral Sentiment: HubSpot raised or maintained third-quarter EPS guidance at $3.25-$3.27, above the $2.80 consensus estimate, but revenue guidance of $924 million-$925 million is slightly below the $925.2 million consensus. The company also reaffirmed full-year 2026 guidance, providing some stability despite the restructuring.
- Negative Sentiment: The layoffs are weighing on sentiment because they underscore pressure to reorganize the business around AI and could create execution, employee-retention, and transition risks. The $65 million-$75 million restructuring expense will also weigh on near-term results. HubSpot layoffs and AI restructuring
- Negative Sentiment: Cantor Fitzgerald maintained a “neutral” rating and set a $200 price target, below the recent share price. The cautious target contrasts with Needham’s bullish view and indicates that analysts remain divided over HubSpot’s valuation and AI transition. HubSpot keeps Neutral rating at Cantor Fitzgerald
HubSpot Company Profile
(
Get Free Report)
HubSpot, Inc develops customer relationship management (CRM) software and related tools designed to help businesses attract, engage and retain customers. Its cloud-based platform brings together marketing, sales, customer service, content management, operations and commerce capabilities, allowing organizations to manage customer interactions across the business.
The company's products include tools for marketing automation, email marketing, lead generation, sales pipeline management, customer support, website and content management, analytics, payments and business operations.
Further Reading
This instant news alert was generated by narrative science technology and financial data from MarketBeat in order to provide readers with the fastest reporting and unbiased coverage. Please send any questions or comments about this story to contact@marketbeat.com.
Before you consider HubSpot, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and HubSpot wasn't on the list.
While HubSpot currently has a Hold rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
The AI boom extends far beyond the biggest tech names. Discover 10 companies supplying the memory, storage, networking, semiconductor manufacturing, and power infrastructure that make AI possible. Learn where the next wave of AI investment opportunities may emerge—and the key risks investors should watch as the global AI buildout accelerates.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.
